How Often Does the IRS Seize Cars and Property? FY2025 Data
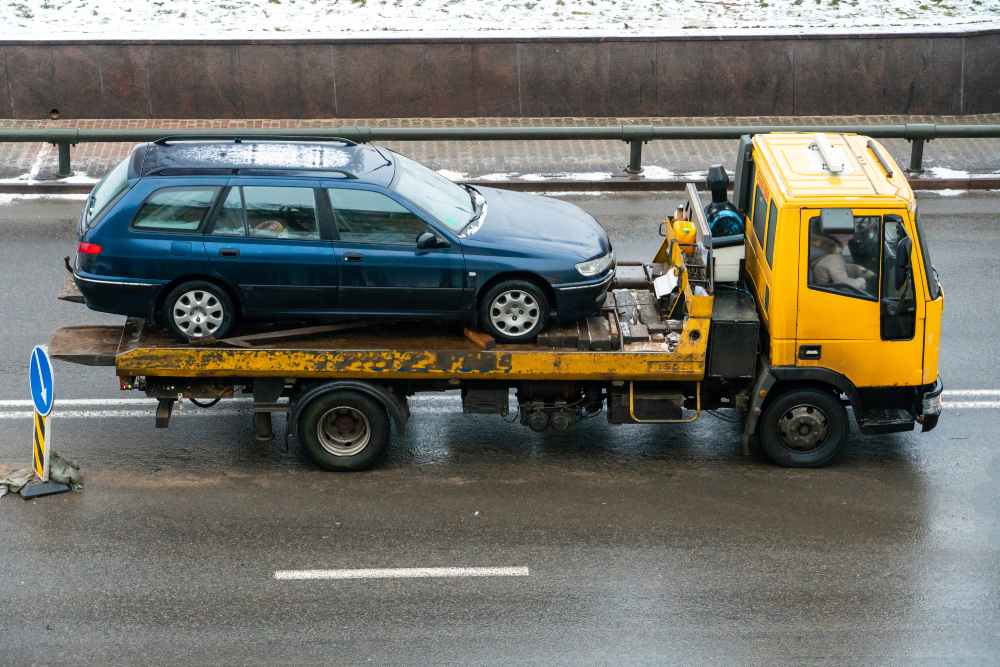
The IRS seizes property very rarely. It made 50 seizures in fiscal year 2025 and averaged 75 a year over the last five years, while it issues around 300,000 levies a year on wages and bank accounts (TIGTA). Cars are a small share of those few seizures. The taxpayers involved typically owe hundreds of thousands or millions of dollars and have ignored repeated notices.
Below are the year-by-year numbers, who actually gets seized, why seizures became so rare, and what still puts a taxpayer at risk.
How often does the IRS seize property?
Seizures, where the IRS physically takes and sells property such as real estate or a vehicle, have fallen to their lowest point in decades. The Treasury Inspector General for Tax Administration (TIGTA), which reviews IRS seizures every year, reports these counts:
Fiscal year | IRS seizures |
2021 | 96 |
2022 | 89 |
2023 | 68 |
2024 | 71 |
2025 | 50 |
Source: TIGTA Report 2026-300-043 (August 2026). The IRS fiscal year runs October 1 to September 30.
The FY2023 figure was first published as 65. TIGTA later found three seizures had been left out, and the IRS revised its Data Book to 68 (TIGTA Report 2025-300-043; IRS Data Book revision).
For scale, the IRS had millions of delinquent accounts on its books. At the end of FY2022, its inventory held 6.7 million delinquent account modules, where each module is one tax period rather than one person (TIGTA). Against that, fewer than 100 seizures a year is a tiny fraction.
How often does the IRS seize cars?
The IRS does not publish a count of vehicle seizures. Its statistics group all seizures together. TIGTA's annual reviews give the closest look:
• From July 2023 to June 2024, 15 of the 105 seizures TIGTA reviewed were vehicles (TIGTA 2025-300-043).
• From July 2022 to June 2023, 4 of the 73 seizures reviewed were vehicles (TIGTA 2024-300-054).
Based on those samples, our estimate is that the IRS seizes somewhere between a handful and about 15 vehicles a year nationwide. That is an extrapolation, not an official figure.
Most seized property is real estate. In the 2023 to 2024 review, 66 of 105 seizures were real property other than a home, and 20 were residences that were not the taxpayer's main home. TIGTA found no seizures of a taxpayer's main home in that sample or the one before it.
If your car is financed, the odds drop further, because the IRS can only take your equity. We explain how that works in can the IRS seize a financed car.
Seizures vs levies vs liens: what the IRS does far more often
Many people use "seize" for any IRS collection action, but the IRS uses three different tools, and the numbers are very different.
Action | What it does | How often |
Notice of Federal Tax Lien | Public claim against your property; it doesn't take anything | 182,156 filed from July 2023 to June 2024 |
Levy | Takes money held by others, such as wages or a bank account | About 314,000 in FY2024 |
Seizure | Takes and sells physical property, such as a car or real estate | 71 in FY2024 |
Sources: TIGTA 2025-300-034 (liens), TIGTA 2025-300-042 (levies), TIGTA 2026-300-043 (seizures).
In FY2024, that works out to roughly 4,400 levies for every seizure. Almost all levies are automated: from July 2023 to June 2024, TIGTA counted 291,928 systemic levies against 611 manual ones (TIGTA 2025-300-042). If you owe and ignore your notices, a bank or wage levy is the realistic risk. Our guide to IRS bank levies vs wage garnishment covers those.
How IRS seizures have changed since the 1990s
Seizures used to be common. TRAC, a research center at Syracuse University that tracks IRS data, reports more than 10,000 seizures a year in the early and mid-1990s (TRAC):
Fiscal year | IRS seizures |
1992 | 11,033 |
1997 | 10,090 |
1998 | 2,307 |
1999 | 161 |
2000 | 74 |
2005 | 512 |
2010 | 605 |
2016 | 436 |
2017 | 323 |
2019 | 228 |
2020 | 77 |
TRAC compiled these from internal IRS reports and Data Books and cautions that the IRS revised its figures from FY2000 on, so treat older numbers as approximate. The sharp drop after 1997 lines up with the IRS Restructuring and Reform Act of 1998, which added taxpayer protections to the collection process.
The decline since 2016 tracks staffing. TIGTA says the drop in seizures "generally coincides with a decline in revenue officers," the field employees who handle seizures. The IRS small business and self-employed division had lost 611 revenue officers as of March 2025 (TIGTA 2025-300-043).
Why IRS seizures are so rare
Staffing is one reason. The rules are the other. Before a revenue officer can seize property, the Internal Revenue Manual requires them to:
1. Verify the debt and confirm you received the required notices.
2. Consider alternatives, such as a payment plan or an offer in compromise.
3. Confirm there is equity. The officer estimates a forced-sale value, generally 60% of fair market value, and subtracts loans and sale costs. If nothing would be left for the tax debt, the officer cannot recommend seizure.
4. File a Notice of Federal Tax Lien first.
5. Try to contact you personally by phone or visit.
6. Get a manager's approval, plus area director approval for an individual's business-use vehicle.
Source: IRM 5.10.1 (revised September 2024).
IRS policy also aims seizures at taxpayers who "won't pay." Seizure "is not pursued for 'will pay' or 'can't pay' taxpayers," and it is not used when it would cause economic hardship or when you qualify for a streamlined payment plan (IRM 5.10.1).
Homes get extra protection. The IRS cannot levy your main home without written approval from a federal district court judge or magistrate, and a residence is exempt when the levy is $5,000 or less (26 USC 6334).
Who actually gets their property seized?
The taxpayers in TIGTA's samples owe far more than most people behind on taxes:
Review period | Seizures reviewed | Balances owed |
July 2023 to June 2024 | 105 seizures of 61 taxpayers | About $19,000 to over $15 million; average over $1 million |
July 2024 to June 2025 | 49 seizures of 44 taxpayers | About $40,000 to over $25 million; average nearly $2.2 million |
Sources: TIGTA 2025-300-043; TIGTA 2026-300-043.
The 2024 to 2025 sample included cash register proceeds, a sign that some seizures involve operating businesses.
Factors that raise the risk, based on the IRS rules above:
• A large balance with real equity in property the IRS can sell.
• Ignoring the Final Notice of Intent to Levy and the revenue officer's contact.
• A case assigned to a field revenue officer rather than automated collection.
• No payment plan, offer or hardship request on file.
Seizures aren't always done right
TIGTA's reviews find the IRS generally follows the law but still makes mistakes. In the 2024 to 2025 review, procedural errors led the IRS to release property worth nearly $377,000 in three cases. In all eight seizures of homes where tenants lived, revenue officers did not follow the procedures meant to protect those tenants (TIGTA 2026-300-043). The prior review found proceeds misapplied for eight taxpayers (TIGTA 2025-300-043).
If the IRS seizes your property, you have appeal rights and can ask a tax professional to check whether every step was followed.
What happens before the IRS seizes anything
A seizure comes at the end of a long process. You get a bill first, such as a CP14 notice saying you owe (IRS), followed by reminders. A CP504 notice is a notice of intent to levy, but on its own it allows only a levy on a state tax refund (Taxpayer Advocate Service). See our page on the IRS CP504 notice.
Before seizing other property, the IRS must send a Final Notice of Intent to Levy and Notice of Your Right to a Hearing, usually Letter 1058, LT11 or CP90, at least 30 days ahead (IRM 5.10.1; 26 USC 6331). You then have 30 days to request a Collection Due Process hearing.
The IRS generally has 10 years from the date a tax is assessed to collect it. Pending payment plan requests, offers in compromise, appeal hearings and bankruptcy pause that clock (IRS).
How to make sure it never happens to you
Respond to notices and get a resolution on file. Any of these takes seizure off the table for most people:
Option | 2026 basics |
Short-term payment plan | Balances under $100,000, paid within 180 days; no setup fee |
Long-term payment plan | Balances of $50,000 or less; $29 online setup with direct debit, $69 online without |
Offer in compromise | $205 application fee; 20% down for a lump-sum offer; the IRS accepted 5,464 of 38,797 offers in FY2025 |
Currently not collectible | Paying would leave you unable to meet basic living expenses; interest and penalties continue |
Sources: IRS payment plans, IRS offer in compromise, IRS Data Book FY2025, IRS delay collection. Fees checked October 28, 2026; fees are higher by phone, mail or in person, and low-income filers pay less.
Learn more about how an IRS offer in compromise works, or follow the steps in how to prevent levy and seizure of property by the IRS.
Ooraa, Inc. is a lead generation and marketing company. We do not resolve tax debts ourselves, but we can connect you with third-party tax resolution providers. See our IRS property seizure page.
The bottom line
An IRS seizure of a car or other property is one of the rarest events in tax collection, with 50 seizures in all of fiscal year 2025. The real risk for most people who owe is a wage or bank levy. Answering notices and setting up a payment plan, offer or hardship status protects you from both.
Frequently asked questions
How often does the IRS seize property?
Rarely. The IRS made 50 seizures in fiscal year 2025 and averaged 75 a year from FY2021 to FY2025, according to TIGTA. It issues around 300,000 levies a year on wages and bank accounts, which are far more common.
How often does the IRS seize cars?
The IRS does not publish a separate count. TIGTA's samples found 15 vehicles among 105 seizures in one recent year and 4 among 73 in the year before. That suggests a handful to about 15 car seizures a year nationwide.
How much do you have to owe before the IRS seizes property?
There is no set dollar threshold. The IRS must find equity worth selling after loans and costs. In TIGTA's recent samples, seized taxpayers owed from about $19,000 to over $25 million, with averages of $1 million to $2.2 million.
Can the IRS seize my house?
Only with written approval from a federal district court judge or magistrate if it is your main home, and not at all if the levy is $5,000 or less. TIGTA found no seizures of a taxpayer's own main home in its 2022 to 2024 samples.
Will the IRS seize property without warning?
No, except in rare jeopardy cases. The IRS must send a Final Notice of Intent to Levy at least 30 days before a seizure, and a revenue officer must try to contact you personally.
Ready to Get Started?
Get a free consultation with a certified debt consultant to see if debt settlement is right for you.
Get Free ConsultationAbout the Author
Bhupinder Bajwa
Bhupinder Bajwa is a Certified Debt Specialist and Financial Counselor with over 10 years of experience helping families overcome financial challenges. Having worked extensively with the South Asian community in the U.S., he understands the cultural nuances and unique financial hurdles they may face. He is passionate about offering clear, compassionate, and actionable guidance to help individuals and families achieve their goal of becoming debt-free.
Related Articles
How to Remove Old Debt From Your Credit Report
11 min read
How to Use a Debt Validation Letter to Protect Yourself
10 min read
How to Settle SBA Loan Debt: Complete Guide to Debt Relief Options
11 min read
What to Know Before Getting a Debt Consolidation Loan
10 min read
Low Income Debt Relief Programs And Options
14 min read
The Ultimate Guide To Side Hustles To Pay Off Debt
12 min read
Get Your Free Consultation
Speak with a certified debt consultant to explore your options.
Start NowNo obligation • Free consultation