How to Negotiate Your Credit Card Debt
Credit card debt can pile up fast. Between interest charges, late fees, and minimum payments, it can feel like you're barely making a dent in what you owe. If you're having trouble keeping up, talking to your credit card company might help. They may agree to lower your interest rate, waive some fees, offer a hardship plan, or let you settle the debt for less than the full amount. Of course, there's no guarantee they'll say yes.
It depends on things like your payment history, income, total balance, and what you can afford to pay. Before you call, take a good look at your finances and figure out how much you can realistically manage. It's also a good idea to have your account details ready. Knowing your options before you start the conversation can make things easier. Let's look at how to negotiate your credit card debt, what to say to your creditor, and what mistakes to avoid along the way.
Know Your Numbers and Your Position
A good call starts before you pick up the phone. Ten minutes of preparation can change how the whole conversation goes.
Build a one-page debt snapshot
On a single page, write down everything about the card:
The name of the card company
Your current balance
Your interest rate (APR)
Your minimum payment and due date
Where the account stands: current, behind, "charged off," or sent to collections
You'll find most of this on your latest statement or in the app. If you have several cards, make one page for each. Having your numbers ready shows you're serious, and it keeps you steady when the representative starts asking questions.
Work out what you can actually pay
Be honest and practical. Add up your monthly income, subtract rent, groceries, utilities, transport, and other must-pay bills, and calculate your debt-to-income ratio to see what's left. Don't leave out the money you send to family back home or regular family commitments.
Also decide whether you could pull together a one-time lump sum, from savings, a bonus, or help from relatives. That number matters a lot if settlement comes up.
Know who you are talking to
The rules and flexibility depend on who holds your debt. The original creditor is the bank that issued your card, and it's usually the best place to start. A debt collector works on the bank's behalf. A debt buyer bought your old debt, often for much less than you owe, so learning how to negotiate with collection agencies can help you secure a lower payment. On your first call, ask: "Who owns this debt right now?"
What Can You Realistically Negotiate?
Many card companies offer hardship programs for people hit by job loss, illness, a family emergency, or a sudden drop in income. Help can include a temporary lower interest rate, waived late or over-limit fees, and a smaller minimum payment for a few months. Programs differ by company, and approval isn't guaranteed, but asking costs nothing. These programs tend to work best when you're still making payments or have only just fallen behind.
Payment plans and settlements
A payment plan means you still repay the full balance, just on easier terms, such as smaller monthly payments over a set period. A settlement means the company agrees to accept less than the full amount as payment in full. Settlements are usually offered only when an account is seriously behind, and they come with costs to your credit and sometimes your taxes. Think of a payment plan as the gentler fix and a settlement as a last resort as you compare all your debt relief options.
Your options at a glance
Option | Best for | Credit impact | Tax impact | Typical timeline |
Hardship program | Temporary setbacks | Usually small | None | A few months |
Payment plan | Steady income, high balance | Small to moderate | None | 1 to 5 years |
Settlement | Seriously behind, lump sum available | Significant | Possible taxable income | Weeks to months |
Nonprofit debt management plan | Several cards, can pay in full over time | Moderate at first, improves | None | 3 to 5 years |
How to Negotiate With Your Credit Card Company, Step by Step
Step 1: Call the right department
When the phone menu starts, don't stay in general customer service. Say or press for "hardship" or "recovery." Those teams have more power to change your terms. Call during the week, when you have 30 minutes and a quiet place to talk.
Step 2: Use a call script
You can adapt this script. Speak calmly and keep it simple.
Opening: "Hello, I'd like to talk about a hardship arrangement for my account."
Your situation: "My income dropped [or: I had a medical emergency / I'm supporting my family], and I'm struggling to keep up with the payments. I want to pay what I owe, and I need help making that possible."
You ask: "Could you lower my interest rate to [number] percent for 12 months and waive the late fees?"
If they offer less: "What's the lowest monthly payment you can set up?"
Closing: "Please send the agreement in writing so I can review it before I make any payment."
If they say no: "Is there another department or program that can review my situation? Could you note my request on the account?"
A "no" from one representative isn't always final. It's fine to call back and ask again.
Step 3: Get it in writing before you pay
Never send a settlement payment based on a spoken promise. Wait for a written agreement that states the amount, the due date, and that the payment settles the account in full (if that's the deal).
Step 4: Keep records
Write down the date, the representative's name, and any reference number. Save every letter and email. If there's a dispute later, these notes protect you.
Common mistakes
Paying a settlement before you have it in writing
Giving the company access to your bank account
Agreeing to a payment you can't keep up
Ignoring calls and letters, which only makes things harder
Debt Settlement: How It Works and What It Really Costs
When settlement makes sense
Understanding the key benefits of settling your debt is helpful when your account is already seriously behind, your hardship is real and likely to last, and you have a lump sum available. If you can still afford a payment plan, that's usually the safer path.
Worked example
This is an illustration, not a promise. Every case is different.
Suppose you owe $8,000. After some back-and-forth, the card company agrees to accept $4,400 as payment in full. You've saved $3,600 on the balance. But the account will likely be marked "settled for less than the full amount" on your credit report. And the $3,600 that was forgiven could be counted as income. If you're in the 22% federal tax bracket and don't qualify for an exception, that could mean roughly $800 in extra tax. So the real savings are smaller than they first appear.
Credit score consequences
Late payments and settled accounts can lower your score, and they can stay on your credit report for up to seven years. The damage usually fades over time, and you can rebuild with on-time payments on a small secured card or credit-builder loan.
Forgiven debt can be taxable
When a lender grants credit card debt forgiveness of $600 or more, it generally has to report it to the IRS on Form 1099-C, and you may owe tax on the forgiven amount. If your debts were greater than your assets when the debt was canceled, you may qualify for an exception called the insolvency exclusion. The IRS explains this on its page about canceled debt (Topic 431). Check with a tax professional before you file.
Alternatives to Direct Negotiation
Nonprofit debt management plan
A nonprofit credit counseling agency, such as one affiliated with the National Foundation for Credit Counseling (NFCC), can review your whole budget for free or a low fee. If you qualify, they may set up a debt management program: they ask your card companies to lower your interest rates, and you make one monthly payment to the agency, which pays your creditors. Plans commonly run three to five years.
Balance transfers and consolidation loans
A balance transfer card or a personal loan with a lower rate can make payments easier. But you generally need a decent credit score to qualify. If you're new to the US or your credit file is thin, this may not be an option. Watch for transfer fees, and don't run up the old cards again.
Bankruptcy as a last resort
Bankruptcy is a legal process that can wipe out or reorganize debt. Deciding between Chapter 7 or Chapter 13 bankruptcy depends on your income and assets: Chapter 7 is a fast process that clears many unsecured debts, while Chapter 13 sets up a three- to five-year repayment plan. . Both seriously affect your credit and have strict rules. If you're considering it, speak with a licensed bankruptcy attorney. Many offer a free first consultation.
Special Considerations for South Asian Households in the US
Some parts of this problem look different when your family lives across two countries. Here are the ones that come up most often.
Thin or no credit history
If you arrived recently on an H-1B, F-1/OPT, or dependent visa, you may have a short credit file. That means fewer backup options, like consolidation loans, so a hardship plan or nonprofit counseling is often the more realistic route. It also means one missed payment can hurt more than you'd expect. Call early.
Family obligations and remittances
Supporting parents, helping a sibling with school fees, or contributing to a wedding are real responsibilities. When you explain your hardship, be truthful about these costs. Your budget has to show what you can actually pay each month. A plan that ignores family obligations will fall apart in a few months.
Stigma and informal borrowing
Many people wait too long to call because they don't want anyone to know. Others borrow from friends, relatives, or community lending circles to cover card payments. That can feel safer, but it also puts important relationships at risk if you can't repay on time. Talking to your card company or a neutral counselor first can keep the problem smaller and private.
Moving or returning home
If you plan to leave the US, unpaid card debt doesn't disappear. It can be sent to collections, and your US credit history doesn't travel with you. If you ever return or apply for credit here again, an unresolved debt can cause problems. If you're worried about how debt connects to your visa or immigration status, ask an immigration attorney.
Language and trusted help
You have the right to understand what you're agreeing to. When you call a card company or counselor, ask if an interpreter or someone who speaks your language is available, and ask for everything in writing. To find a nonprofit counselor, start with the NFCC website, and check which languages each agency supports before you book.
Know Your Rights and Avoid Debt Relief Scams
Your rights with collectors
The Fair Debt Collection Practices Act and the CFPB's Regulation F protect you from abusive collectors. A collector must send you a written notice about the debt. If you dispute it within 30 days of getting that notice, the collector has to stop collecting until it verifies the debt. Collectors can't threaten you, harass you, lie about what you owe, or call at unreasonable hours (generally before 8 a.m. or after 9 p.m. your time). You can also tell a collector in writing to stop contacting you.
Statute of limitations on old debt
Every state sets a time limit for how long a creditor can sue you over a debt. It varies by state and by type of debt. In some states, making a small payment or admitting in writing that you owe the debt can restart that clock. Before you pay or sign anything on an old debt, check your state's rules or speak with a consumer attorney.
Red flags
Be careful with any company that:
Asks for fees before it has settled or reduced any of your debt
Guarantees it can wipe out your debt
Tells you to stop paying your creditors without explaining the risks
Pressures you to sign right away
For phone-based debt relief services, the FTC's rules generally forbid charging fees before results. You can verify a company or report a problem with the FTC or the CFPB.
Conclusion and Next Steps
Negotiating your card debt can feel scary, but it's often easier than people expect. Here's a simple plan:
Gather your numbers. Fill out your one-page debt snapshot and work out what you can pay.
Call the hardship department. Use the script above and make one clear request.
Get the terms in writing. Don't pay until you have the agreement and have read it.
If you have several cards or feel stuck, reach out to Ooraa for a free debt relief consultation (available in English, Hindi, Punjabi, Urdu, Bengali, Tamil, Telugu, and Gujarati) or speak with a nonprofit credit counselor. You can also keep a simple call log so every conversation is documented. This article is for general information only and isn't legal, tax, or financial advice. Your situation is unique, so consider talking with a qualified professional.
Ready to Get Started?
Get a free consultation with a certified debt consultant to see if debt settlement is right for you.
Get Free ConsultationAbout the Author
Bhupinder Bajwa
.
Related Articles
What Ignoring Credit Card Debt Really Costs You
10 min read
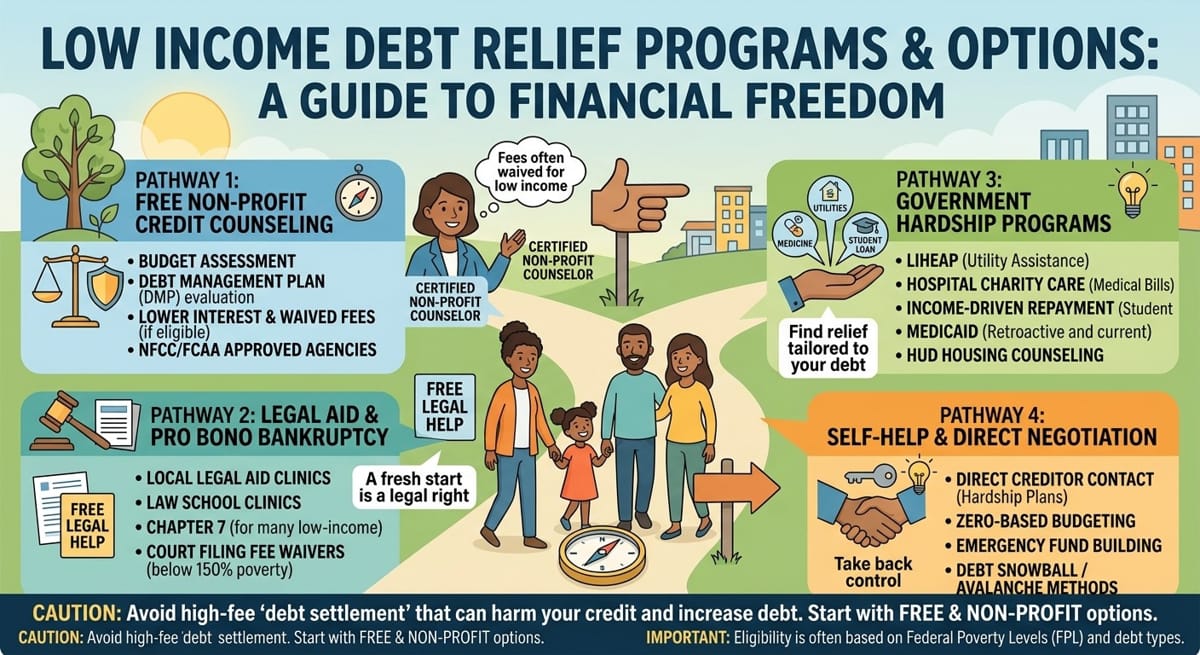
Low Income Debt Relief Programs And Options
14 min read
What Debts Can Be Included in Debt Relief?
13 min read

Debt Settlement for $20,000 in Credit Card Debt: What to Expect
11 min read
What’s The Difference Between Debt Consolidation And Debt Settlement?
12 min read
What Happens If You Can’t Pay Your Business Credit Card?
11 min read
Get Your Free Consultation
Speak with a certified debt consultant to explore your options.
Start NowNo obligation • Free consultation