Pros and Cons of Using a Personal Loan to Pay Off Credit Card Debt
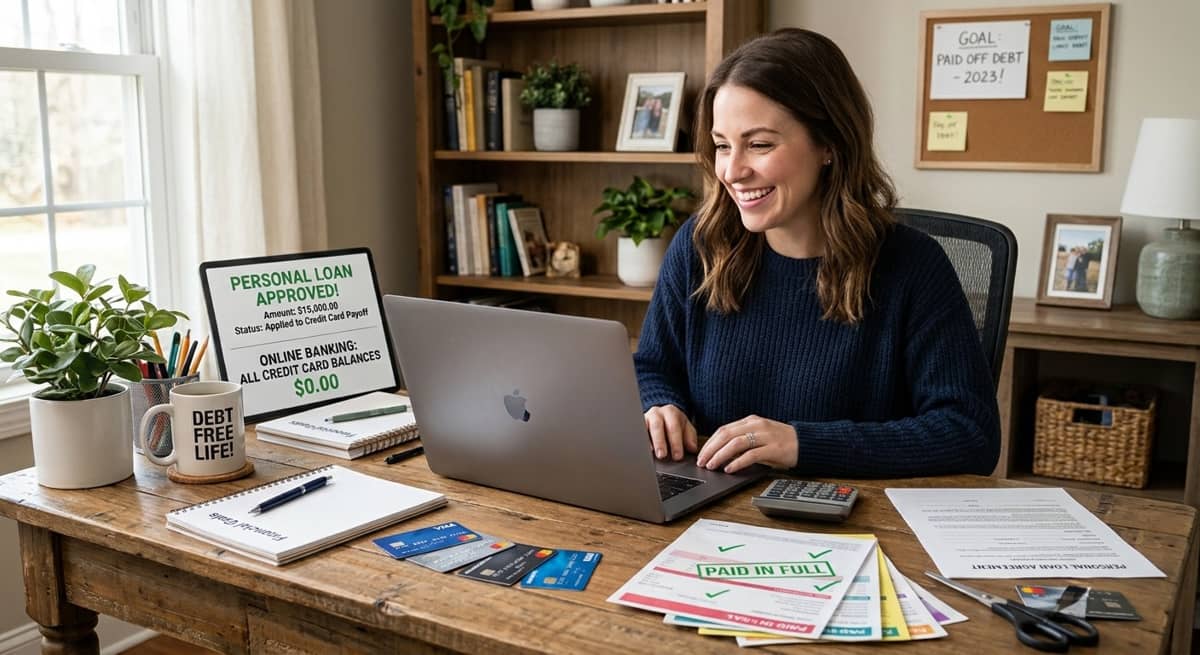
Credit card debt can quickly become stressful, especially when you're dealing with high interest rates and several monthly payments. If you're finding it hard to keep up, taking out a personal loan might seem like a good way to make things easier. It lets you combine multiple credit card balances into one monthly payment, often with a lower interest rate and a fixed repayment period.
This can make managing your money simpler and help you see when you'll be debt-free. But there's a downside, too. Personal loans can come with extra fees and interest costs, and if you start using your credit cards again, you could end up with even more debt.
So, before choosing this option, it's worth looking at both sides. Let's break down the pros and cons of using a personal loan to pay off credit card debt and see if it's the right move for you.
What It Means to Use a Personal Loan to Pay Off Credit Card Debt
Using a personal loan to pay off credit cards is often called debt consolidation, and it helps to understand when debt consolidation can really help before you apply. . You borrow a set amount from a bank, credit union, or online lender. You use that money to pay off your credit cards. Then you repay the loan in equal monthly payments over a fixed time, usually two to five years.
Credit cards are revolving debt. Your balance goes up and down, and the interest rate can change. A personal loan is installment debt. The amount, the rate, and the end date are set at the start.
Two terms are worth knowing. APR is the yearly cost of borrowing, including interest. An origination fee is a one-time charge, often taken out of the loan before you receive the money.
If you want to compare this with other paths, see our guide on what debt relief loans are and how they compare or explore your debt relief options.
Why This Decision Can Feel Different for South Asians in the U.S.
Many people who move to the U.S. start with little or no credit history. That is true for people on work visas such as H-1B or H-4, students on F-1 or OPT, and new green card holders. Even if you had a strong credit record back home, it usually does not carry over automatically. A short U.S. history can make it harder to get approved or to get a low rate. Lender rules differ, so check each lender's requirements before you apply. Some services can help bring over credit history from another country, so ask about them.
Family obligations, remittances, and informal borrowing
Money often involves more than one household. You may send support to parents or relatives abroad, help with a family event, or cover an emergency far from home. Some people borrow from relatives or community members before turning to a bank. Others carry card balances quietly because debt feels private or awkward to talk about. If that sounds familiar, you are not alone. A fixed monthly payment and a clear end date can make it easier to plan your budget around the people who depend on you.
Pros of Using a Personal Loan to Pay Off Credit Card Debt
Here is what a personal loan can do for you when the numbers work in your favor.
You may pay a lower interest rate
Credit cards often charge 20% or more in interest. Personal loans can cost less, especially if you have good credit. A lower rate means more of each payment goes toward your balance instead of interest. Over a few years, that can save you hundreds or even thousands of dollars. The catch is that your rate depends on your credit score, income, and existing debt. Always check the rate you are actually offered, not just the lowest one advertised.
A fixed payoff date
Credit card minimum payments can keep you in debt for years. A personal loan is different. You know your payment amount and the exact month you will be done. That end date can be motivating. It turns a debt that feels endless into a goal you can see. You can mark it on a calendar and track your progress.
One predictable monthly payment
Juggling several cards means several due dates, rates, and apps to check. One missed date can bring a late fee and a hit to your credit. A single loan payment replaces all of that. It is easier to remember and easier to budget, especially when you are also managing rent, family support, and other regular bills. Autopay can make it even simpler.
A possible credit score boost
Paying off cards with a loan lowers your credit card utilization, which is how much of your available credit you are using. A lower number can help your score. Adding an installment loan can also improve your mix of credit types. Keep in mind that applying can cause a small, temporary dip because of the hard credit check. Making every payment on time matters most in the long run.
No collateral required
Most personal loans are unsecured. You do not have to put up your car, home, or savings as security. That keeps your assets out of the deal. It also means lenders look closely at your credit and income when deciding whether to approve you and what rate to offer. Unsecured does not mean without consequences, though. Missed payments still hurt your credit.
Cons and Risks You Should Weigh First
A personal loan is not the right choice for everyone. Some people end up paying more or falling back into debt. Look at these risks honestly before you apply, so you can decide with your eyes open.
Origination fees and total cost
Many lenders charge an origination fee, often between 1% and 10% of the loan. It is usually taken from the amount you receive. On a $10,000 loan, a 5% fee means you get $9,500 but repay $10,000 plus interest. A low interest rate can look great until the fee is added. Some lenders charge no fee, so shop around. Compare the total cost of each loan, not just the APR.
The rate you are offered may not be lower
The best rates go to people with strong credit. If your score is fair or your debt is high, the rate you are offered could be close to, or even higher than, your card rate. In that case, a loan may not save you anything. You can often check your likely rate with a soft credit check, which does not affect your score. Do that before you commit.
Approval can be harder for newcomers and thin-file borrowers
If you are new to the U.S., approval can be harder. Some lenders want a longer credit history, a certain income, or a specific immigration status. Others may approve of you but at a higher rate. A co-signer can help, but it puts that person on the hook if you miss payments. Think carefully before asking a relative or friend to take on that risk.
It does not fix the habits that created the balance
A loan clears your card balances, but it does not change what caused them. If you start charging again, you could end up with a loan payment and new card debt, one of the most common debt consolidation risks and mistakes. This is sometimes called double debt, and it can be harder to escape than the first round. Before you borrow, look at where the spending came from and make a plan to stop it. A one-time emergency, like a medical bill or a sudden trip home, is different from everyday overspending. Be kind to yourself, but be honest too.
Longer terms cost more, and missed payments have consequences
A longer loan term gives you a smaller monthly payment, but you pay more interest overall. Missing payments can lead to late fees, credit damage, and calls from collectors. A fixed loan payment also has less flexibility than a credit card if money gets tight. Choose a payment you can afford even in a tougher month.
Is the Loan Actually Cheaper?
Let's compare two paths using made-up numbers. Treat this as an illustration, not a quote. Your real numbers will differ.
Imagine you owe $10,000 on credit cards at 24% APR. You are offered a 3-year personal loan at 12% APR with a 5% origination fee. To end up with $10,000 in hand after the fee, you would borrow about $10,500. This example assumes you stop using the cards in both cases.
Keep paying the cards | Use the personal loan | |
Monthly payment | About $350 | About $350 |
Time to pay off | About 43 months | 36 months |
Total interest and fees | About $5,000 | About $2,600 |
In this example, the loan saves roughly $2,400 and gets you debt-free about seven months sooner. Without the fee, the loan would cost less than $2,000 in interest. Change any number, such as a higher rate or a bigger fee, and the savings shrink. Plug your own offer into an online loan calculator before you decide.
Is a Personal Loan Right for You?
Ask yourself these questions honestly.
It may be a good fit if:
The rate and fees you are offered are clearly lower than your card rates
The monthly payment fits your budget with room to spare
Your income is steady
You have a plan to stop adding new card balances
You have at least a small emergency fund, so a surprise bill does not push you back onto cards
Think twice if:
The rate you are offered is close to your card rate
Your income is uncertain, or you may move or change jobs soon
Everyday spending, not a one-time event, caused most of the debt
You mainly want a lower payment and would stretch the loan very long to get it
If you are unsure, talk to a nonprofit credit counselor before you sign anything. Many offer a first conversation for free or at low cost.
Alternatives to Consider
A personal loan is only one way to tackle card debt. Here are other options to look at.
Balance transfer card: Some cards offer 0% interest for a limited time, often 12 to 21 months. Most charge a transfer fee, commonly 3% to 5%. This can work well if you can pay off the balance before the offer ends. If you cannot, the rate can jump.
Nonprofit credit counseling and a debt management plan: A counselor reviews your budget and may set up a plan where you make one monthly payment and the agency works with your card companies, often to lower interest rates. Look for agencies affiliated with the National Foundation for Credit Counseling.
Ask your card issuer for help: Call and explain your situation. Some issuers offer hardship programs with lower rates or smaller payments for a time.
Be careful with debt settlement and retirement money: Debt settlement companies may tell you to stop paying your cards, which can damage your credit and lead to fees or lawsuits. Pulling money from retirement accounts can bring taxes, penalties, or lost growth. Both deserve a very close look first.
Be wary of anyone who promises to erase your debt, asks for large upfront fees, or pressures you to act fast. The Federal Trade Commission and the Consumer Financial Protection Bureau offer free information on spotting these scams.
How to Use a Personal Loan to Pay Off Credit Cards: Step by Step
Add up what you owe. List every card balance and its APR.
Check your credit reports. You can get free reports at AnnualCreditReport.com. Fix any errors you find.
Prequalify with several lenders. Use soft-check tools from banks, credit unions, and online lenders. These do not affect your score.
Compare the total cost. Look at the APR, origination fee, loan term, and monthly payment side by side.
Apply and ask for direct payment. Many lenders send money straight to your card issuers. If yours does not, pay off the cards yourself the same day.
Set up autopay. This helps you avoid missed payments.
Keep the cards open, but put them away. Closing them can lower your available credit and your score. Just avoid new charges.
The Bottom Line and Next Steps
A personal loan can be a powerful tool for paying off credit card debt, but only when the total cost is lower and your spending is under control. Run your own numbers, compare offers, and think about the alternatives before you decide. You do not have to figure it out alone.
Ready to talk through your numbers with someone who understands your situation? Book a free consultation with Ooraa next steps.
Frequently Asked Questions
Will a personal loan hurt my credit score?
It can dip a little at first because of the hard credit check and the new account. Over time, it can help if you pay on time and your card balances stay low. The biggest risks are missed payments and running the cards back up.
Can I qualify on H-1B or OPT, or with a short U.S. credit history?
Maybe. Some lenders approve people with a short U.S. credit history or a work visa, while others require more history or a certain status. Rules change and differ by lender, so compare requirements and use soft-check prequalification where it is offered.
Personal loan vs. balance transfer: which is better?
A balance transfer card can cost less if you can repay within the 0% period. A personal loan is better if you need more time, because the rate and payment stay fixed. Compare the fees and your realistic payoff timeline.
Is debt consolidation the same as debt settlement?
No. Consolidation means borrowing money to pay your debts in full. Settlement means paying less than you owe, often after you stop making payments, which can seriously damage your credit. They work very differently.
What credit score do I need?
It varies by lender. Many look for fair to good credit, often in the mid-600s or higher, and the best rates usually go to scores in the 700s. Lenders also look at your income and other debts. Prequalify to see where you stand.
Ready to Get Started?
Get a free consultation with a certified debt consultant to see if debt settlement is right for you.
Get Free ConsultationAbout the Author
Bhupinder Bajwa
.
Related Articles
How to Negotiate Your Credit Card Debt
11 min read
What Ignoring Credit Card Debt Really Costs You
10 min read
What Debts Can Be Included in Debt Relief?
13 min read

Debt Settlement for $20,000 in Credit Card Debt: What to Expect
11 min read
What Happens If You Can’t Pay Your Business Credit Card?
11 min read
Dismiss Your Credit Card Lawsuit: Winning Strategies
10 min read
Get Your Free Consultation
Speak with a certified debt consultant to explore your options.
Start NowNo obligation • Free consultation