Financial Tips, Guides & Insights Blog
Page 9 of 38
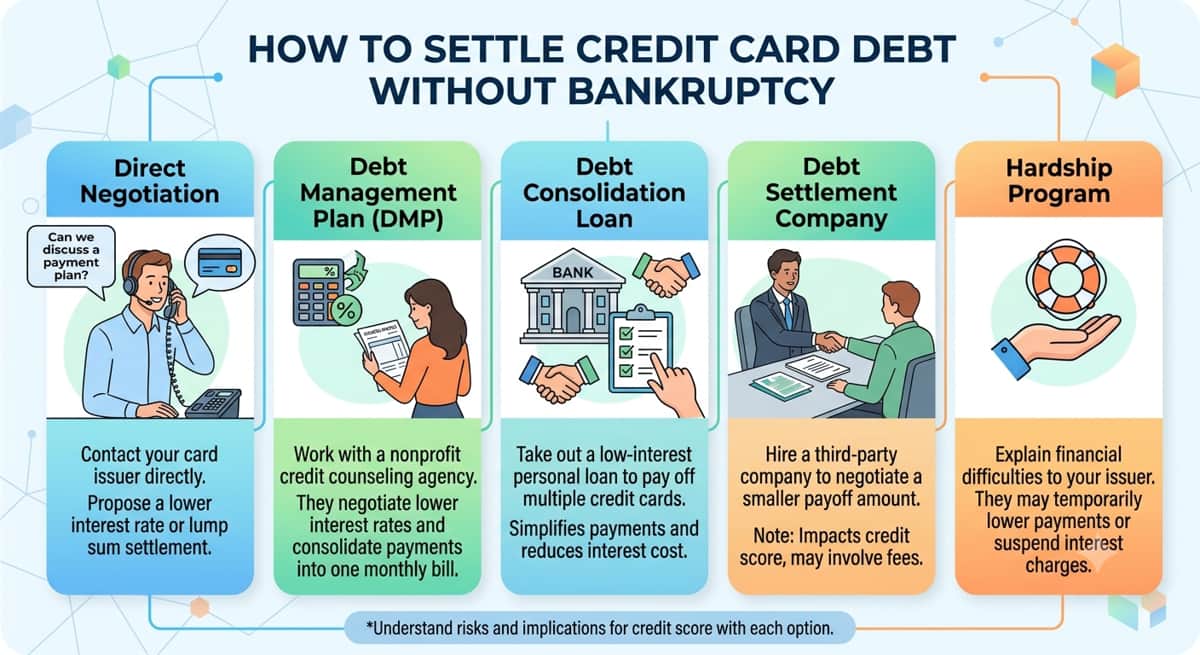
How Can You Settle Credit Card Debt Without Bankruptcy?
You can handle overwhelming credit card debt without filing for bankruptcy. Options include direct negotiation, nonprofit credit counseling, settlement companies, consolidation loans, and balance transfers. While settlement reduces your total debt, weigh the credit impacts and potential taxes. Consulting an NFCC-accredited nonprofit counselor is a safe, low-cost way to start.
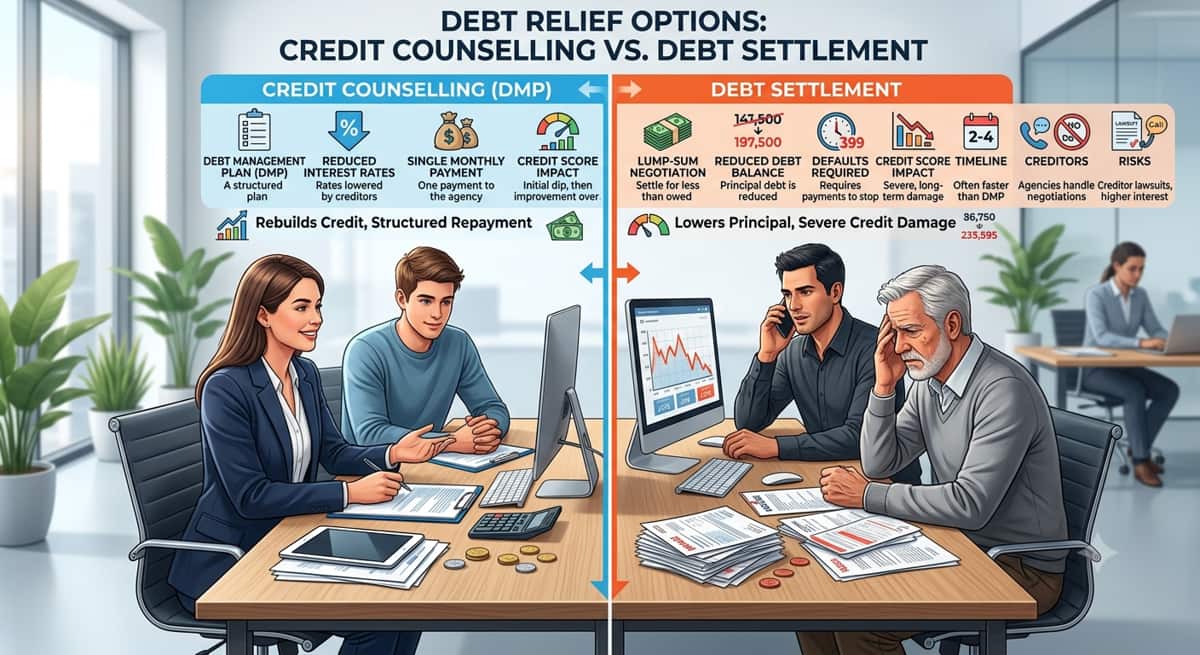
Credit Counselling vs. Debt Settlement: Which One Is Right for You?
Managing debt can feel deeply isolating, especially within South Asian families. To regain control, you have two main paths: credit counseling, which gently restructures your payments through a predictable, credit-safe plan, or debt settlement, which aggressively reduces your principal balance but carries severe credit risks. Ooraa helps you safely choose the right fit.
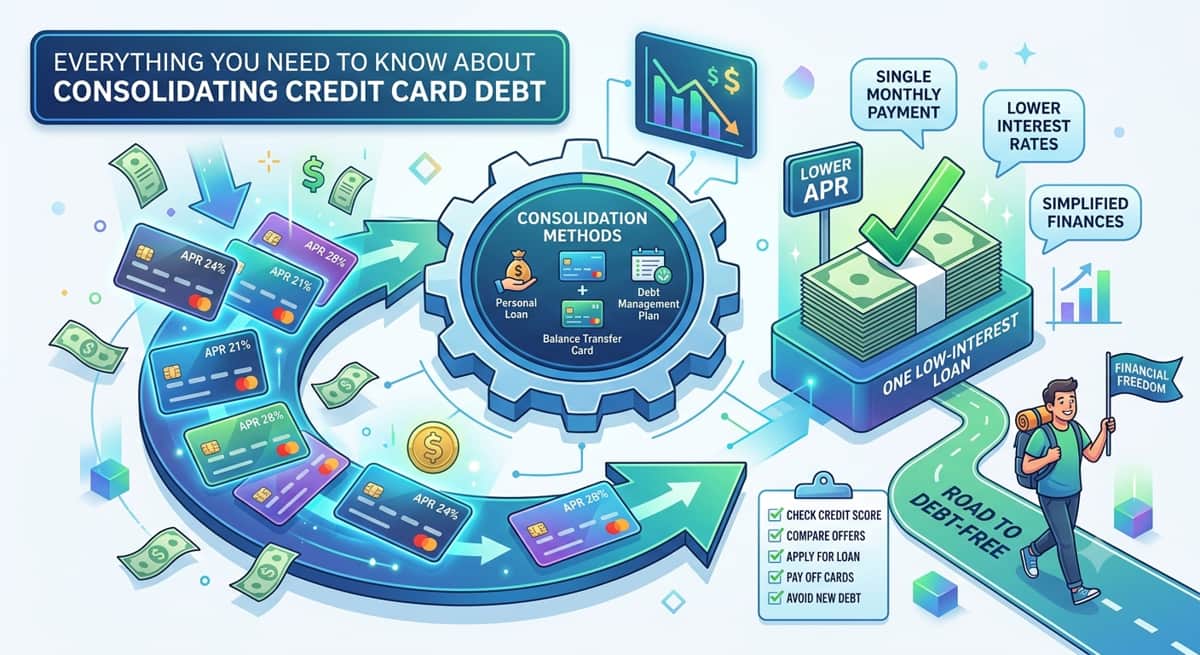
Everything You Need To Know About Consolidating Credit Card Debt
Credit card debt consolidation combines multiple balances into a single monthly payment, simplifying your finances. Main methods include balance transfer cards, personal loans, home equity, and nonprofit debt management plans. While it can lower interest rates and boost your credit score, you must budget to avoid accumulating new debt.
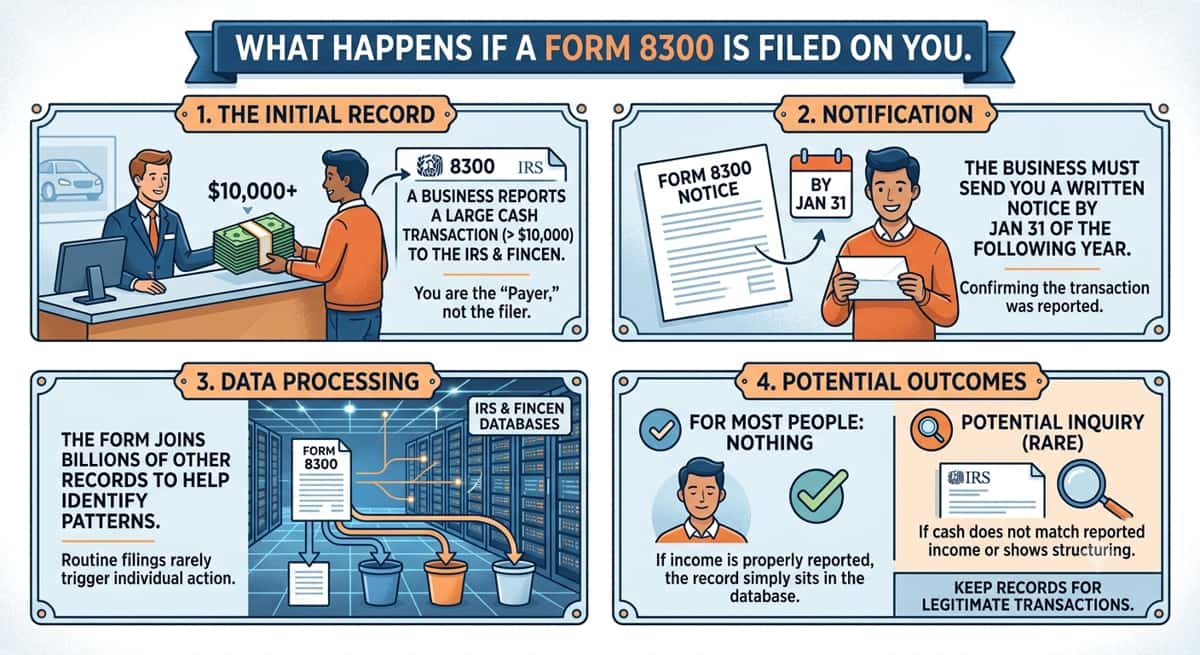
What Happens If A Form 8300 Is Filed On You?
When a business files IRS Form 8300 after a cash transaction over $10,000, it is routine compliance, not an accusation. For most people, nothing happens. To stay secure, confirm your written notice, keep clear records (like gift letters) for five years, and avoid "structuring" transactions to evade the rule.
Credit Card Debt Forgiveness For Disabled: Do You Qualify?
There is no automatic government program to forgive credit card debt for disabled individuals. However, options like issuer hardship programs, nonprofit credit counseling, debt settlement, and bankruptcy provide real relief. Disability benefits are generally protected from creditors. South Asian immigrants should also consider unique cultural factors and avoid predatory scams.
Do Debt Relief Programs Work?
Debt relief programs including counseling, settlement, consolidation, and bankruptcy—help manage debt but carry trade-offs like credit score impacts. For South Asian families, cultural silence and cross-border obligations add distinct challenges. Choosing the right program while avoiding scams is vital, and a nonprofit credit counselor is a safe first step.
Filing For Business Bankruptcy? You Need To Know This First
Filing for business bankruptcy is a legal reset, not a moral failure. Depending on your business structure, options like Chapter 7 (liquidation) or Subchapter V (small business reorganization) can wipe out or restructure debt. Prioritize reviewing personal guarantees, consult both bankruptcy and immigration attorneys, and avoid hiding assets before filing.
Does Debt Affect Your Credit Score?
For South Asian immigrants, avoiding debt in the U.S. hinders financial growth. A strong credit score requires understanding that debt isn’t inherently bad; strategic management is key. To build credit from zero, prioritize on-time payments, keep credit utilization below 30%, and use tools like autopay to secure your family's future.
Is Bankruptcy Discharge Public Record?
For South Asian immigrants in the U.S., financial struggles carry deep cultural stigma, making bankruptcy intimidating. However, it is a legal fresh start, not a public embarrassment. Filed in federal courts (PACER), records require fees and specific details to access meaning neighbors and relatives back home won't easily stumble upon them.
State Tax Debt: What You Need To Know
State tax debt is separate from federal IRS debt and is handled by individual state agencies with unique rules. While it does not directly impact your U.S. immigration status, ignoring it can lead to liens, wage garnishments, or frozen bank accounts. Resolving it quickly through payment plans or professional help protects your financial health.