What You Should Know About Bankruptcy In Puerto Rico?
Is Bankruptcy in Puerto Rico the Same as the Mainland U.S.?
The Two Main Paths: Chapter 7 vs. Chapter 13
Chapter 7: Liquidation
Often called "liquidation" or "straight" bankruptcy, Chapter 7 is designed for individuals with limited income who can't realistically repay their debts. The process involves a court-appointed trustee who reviews your assets. Any "non-exempt" property (assets not protected by law) may be sold, and the proceeds are distributed to creditors. The goal is a quick and complete discharge of most unsecured debts, such as credit card debt and medical bills, allowing you to get a swift financial fresh start. The entire process typically takes about three to six months.Chapter 13: Reorganization
Chapter 13 is a "reorganization" bankruptcy for individuals with a regular, stable income. Instead of liquidating assets, you propose a detailed repayment plan to the court. This plan outlines how you will pay back a portion of your debts over a three-to-five-year period. A key benefit of Chapter 13 is that it allows you to protect valuable assets, like your home or car, while catching up on missed payments. The goal is to restructure your finances and repay your debts in an orderly, manageable way, all while under the court's protection.Chapter 7 vs. Chapter 13: A Comparison
| Feature | Chapter 7 | Chapter 13 |
| Type | Liquidation | Reorganization |
| Goal | Discharge most debts | Repay debts over time |
| Income Test | Means test required | Must have a regular income |
| Duration | 3-6 months | 3-5 years |
| Assets | Non-exempt assets may be sold | Debtor retains assets |
Special Considerations for South Asian Residents
The Bankruptcy Process in Puerto Rico: A Step-by-Step Guide
Step 1: Mandatory Credit Counseling
Before you can file your petition, you must complete an approved credit counseling course. This mandatory briefing must be taken within 180 days before filing and is intended to help you explore bankruptcy alternatives. The course typically takes about an hour and can be easily completed online or by phone through a provider approved by the U.S. Trustee Program.Step 2: Filing the Petition
The next step is officially filing your bankruptcy petition. This substantial package of documents detailing your assets, liabilities, income, expenses, and recent financial transactions must be submitted to the U.S. Bankruptcy Court for the District of Puerto Rico. Filing creates the official start date for your case and must include the certificate from your pre-filing credit counseling course.Step 3: The Automatic Stay
Immediately upon filing your petition, a powerful legal protection known as the Automatic Stay goes into effect. This critical legal order instantly halts most creditor collection actions, including phone calls, collection letters, lawsuits, wage garnishments, and foreclosure proceedings. The Automatic Stay provides immediate and vital breathing room while your case moves forward.Step 4: Meeting of Creditors (Section 341 Meeting)
Roughly one month after filing, you must attend the Meeting of Creditors, or the Section 341 meeting. Despite the name, creditors rarely attend. The primary purpose is for the court-appointed bankruptcy trustee to verify your identity, review your paperwork, and ask you questions under oath about your financial situation. In the District of Puerto Rico, these meetings are often held virtually, typically via video conferencing platforms like Zoom, making attendance easier for individuals across the island. Your attorney will guide you through this process.Step 5: Debtor Education Course
After filing but before receiving your final debt discharge, you are required to complete a second mandatory course: the Debtor Education course (also called a personal financial management course). This course focuses on budgeting, money management, and rebuilding your finances post-bankruptcy. Failing to file the certificate of completion for this course will prevent the court from granting a discharge.Step 6: Discharge
The final, eagerly awaited step is the discharge. This is the court order that legally releases you from your obligation to pay most of the debts included in your case. In a Chapter 7 case, this typically occurs about 60-90 days after the 341 meeting. In a Chapter 13 case, the discharge is granted only after you have completed all scheduled payments outlined in your three-to-five-year repayment plan.Alternatives to Bankruptcy
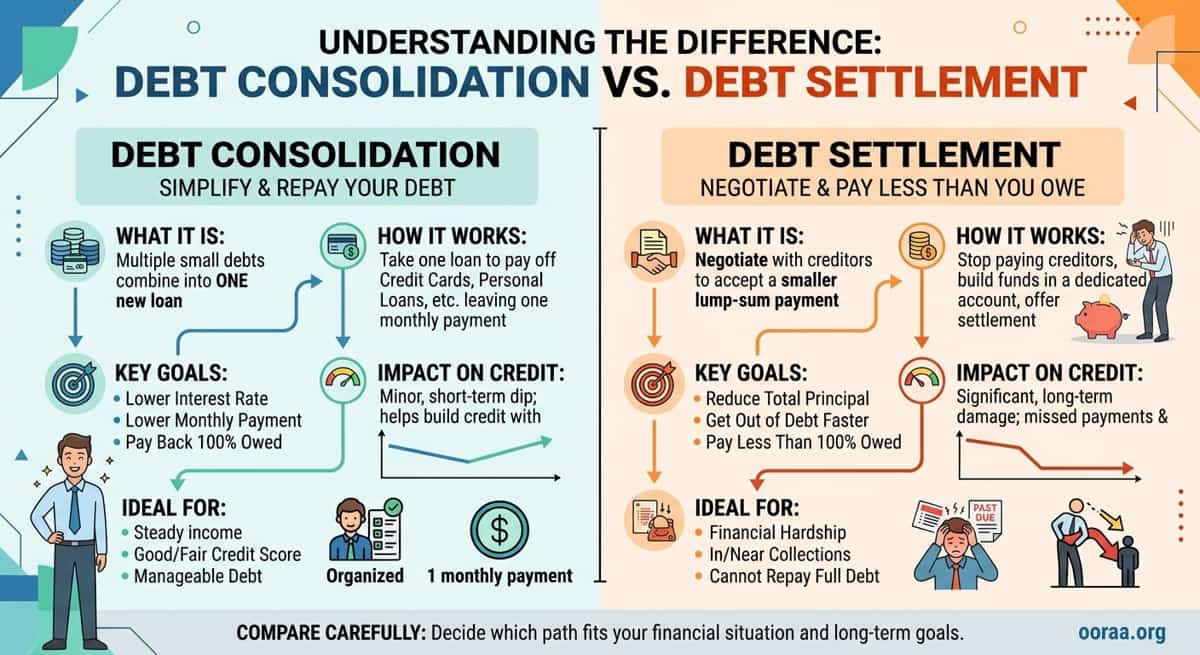
While bankruptcy offers a powerful solution, it is not the only path to debt relief. Exploring all your options can help you find the one that best fits your situation. Debt Consolidation: This involves taking out a new loan to pay off multiple existing debts. The goal is to combine your high-interest debts into a single, lower-interest payment. Many national debt relief companies, including those that serve Puerto Rico, can help you find consolidation loans that may make your monthly payments more manageable and simplify your financial life. Debt Settlement: In this process, a company or lawyer negotiates with your creditors to reduce the total amount of debt you owe. You agree to pay a lump sum that is less than the original amount, and the creditor agrees to consider the debt settled. While this can provide significant relief, it can hurt your credit score and may not be right for everyone. Pro Bono and Low-Cost Services: For individuals with limited income, free or low-cost legal and financial counseling services are available. Organizations like Legal Services Corporation and local non-profits can provide professional advice and representation, helping you explore all your options and potentially avoid costly mistakes.Financial Management for Your Future
Getting a fresh start is just the beginning. The most crucial part of your journey is building a strong financial foundation for the future. This requires a shift in mindset from simply managing debt to actively building wealth and stability. Mastering U.S. Financial Literacy: The U.S. financial system can be complex, and understanding concepts like credit scores, interest rates, and investment options is essential. Take the time to educate yourself through reputable resources. Knowledge is your most valuable asset. Creating a Realistic Budget: The key to long-term financial health is living within your means. A practical budget allows you to track your income and expenses, identify areas where you can save, and allocate funds toward your financial goals. It’s a tool for empowerment, not restriction. Rebuilding Your Credit: After bankruptcy, your credit score will take a hit, but it is not a permanent state. You can rebuild it by making timely payments on any remaining debts and secured credit cards. Showing a pattern of responsible financial behavior over time is the most effective way to improve your credit and open up new opportunities. Seeking Cross-Cultural Financial Planning: It can be incredibly valuable to work with a financial advisor who not only understands the nuances of the U.S. economic system but also respects and understands the unique financial values and family structures of South Asian communities. They can help you create a plan that honors your traditions while paving the way for a prosperous future.Conclusion
Bankruptcy is not the end of your financial story; it is a powerful legal tool for a new beginning. We have explored the nuances of the process in Puerto Rico, which, despite its public debt history, operates under the same federal laws as the rest of the U.S. Remember that the journey from financial stress to stability is a personal one. Still, you do not have to walk it alone. With a clear understanding of your options, a willingness to seek professional advice, and a renewed commitment to your financial health, you can pave a clear path forward. Your fresh start is within reach.Ready to Get Started?
Get a free consultation with a certified debt consultant to see if debt settlement is right for you.
Get Free ConsultationAbout the Author
Bhupinder Bajwa
Bhupinder Bajwa is a Certified Debt Specialist and Financial Counselor with over 10 years of experience helping families overcome financial challenges. Having worked extensively with the South Asian community in the U.S., he understands the cultural nuances and unique financial hurdles they may face. He is passionate about offering clear, compassionate, and actionable guidance to help individuals and families achieve their goal of becoming debt-free.
Related Articles
Low Income Debt Relief Programs And Options
14 min read
The Ultimate Guide To Side Hustles To Pay Off Debt
12 min read
10 Reasons Why You Should Pay Off Debt
9 min read
7 Ways To Get Out Of Business Debt
11 min read
Is 639 A Good Credit Score? How It Affects Loans, Credit Cards And Ways To Improve It
12 min read
What’s The Difference Between Debt Consolidation And Debt Settlement?
12 min read
Get Your Free Consultation
Speak with a certified debt consultant to explore your options.
Start NowNo obligation • Free consultation
Related Posts
- Low Income Debt Relief Programs And Options
14 min read
- The Ultimate Guide To Side Hustles To Pay Off Debt
12 min read
- 10 Reasons Why You Should Pay Off Debt
9 min read
- 7 Ways To Get Out Of Business Debt
11 min read