Financial Tips, Guides & Insights Blog
Page 6 of 38
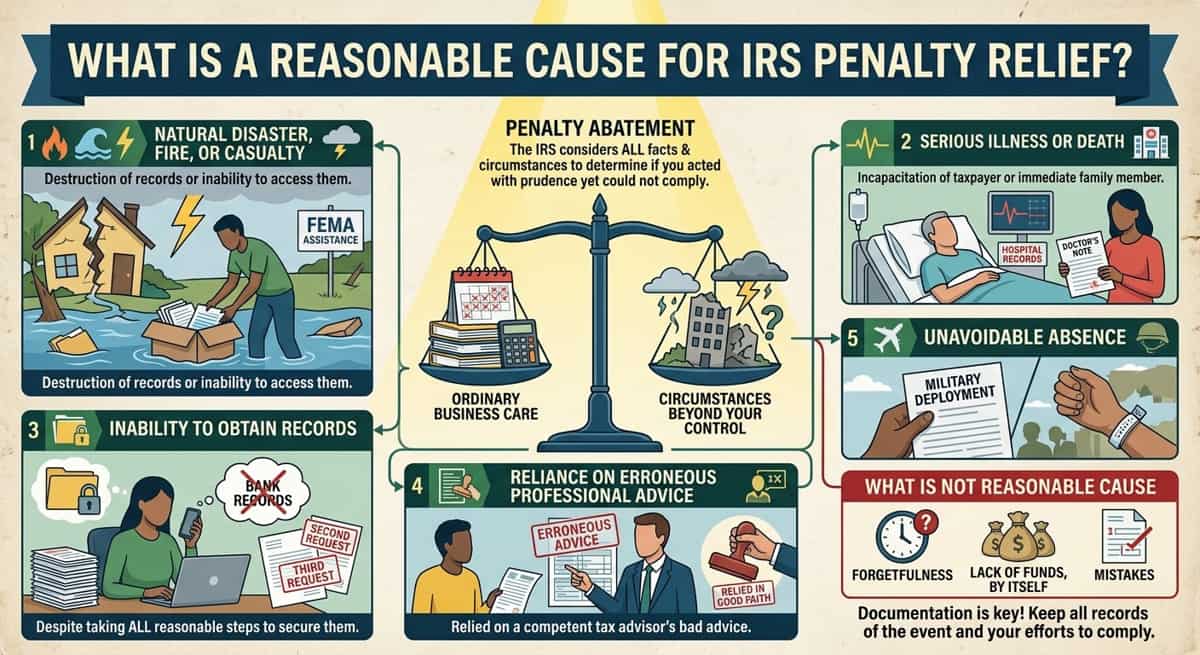
What Is a Reasonable Cause for IRS Penalty Relief
The IRS forgives penalties, though not base taxes, if uncontrollable events like illness, disasters, or family emergencies prevent timely filing. This relief particularly helps South Asian households navigating complex foreign asset reporting or cash-based business rules. Successful claims require clear documentation, though First-Time Penalty Abatement offers an easier alternative.
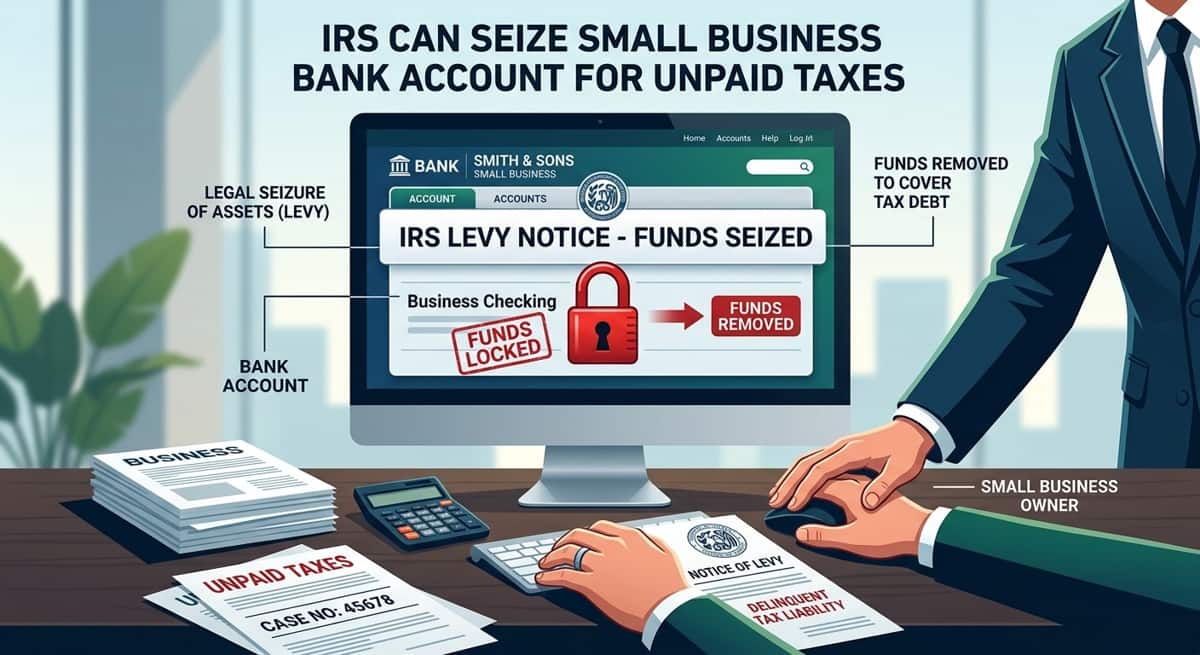
Can the IRS Seize a Small Business Bank Account for Unpaid Taxes?
The IRS can legally freeze and seize small business bank accounts for unpaid taxes, but only after sending required notices like LT11. Once levied, banks hold funds for 21 days before transfer. Business owners can stop or release a levy through installment agreements, hardship claims, or an Offer in Compromise.
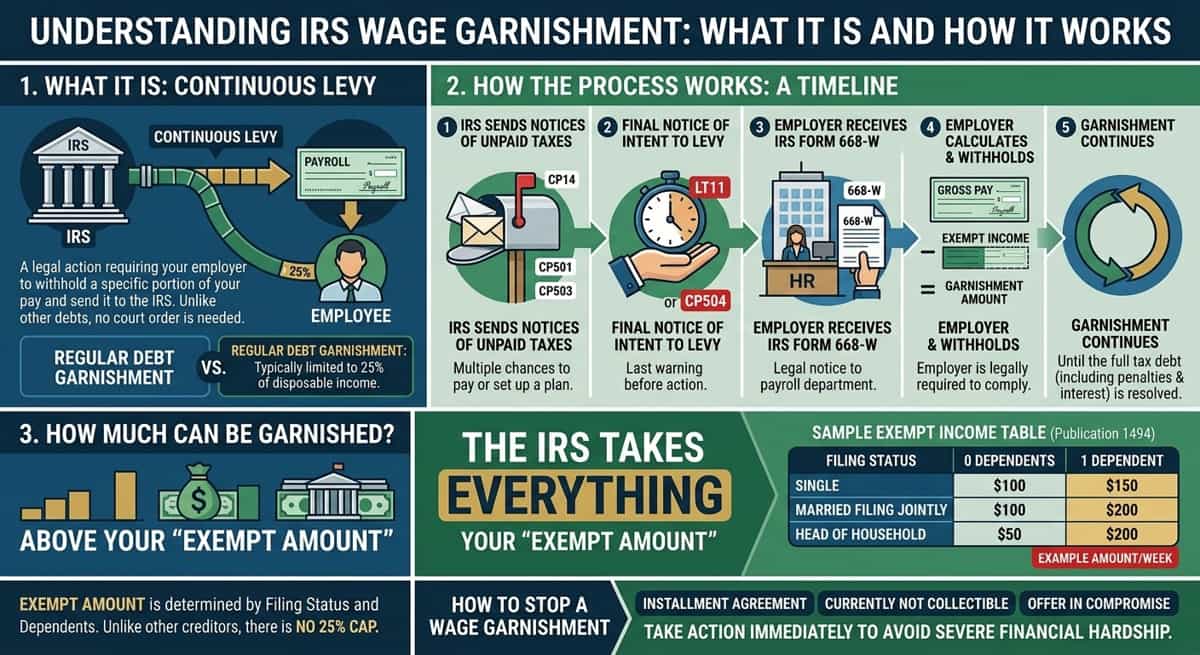
What Is an IRS Wage Garnishment and How Does It Work?
An IRS wage garnishment forces employers to send part of your paycheck to pay back taxes. Without needing court approval, the IRS takes everything above a small exempt threshold. You can stop or prevent it by acting within 30 days of the final notice through payment plans or hardship relief.
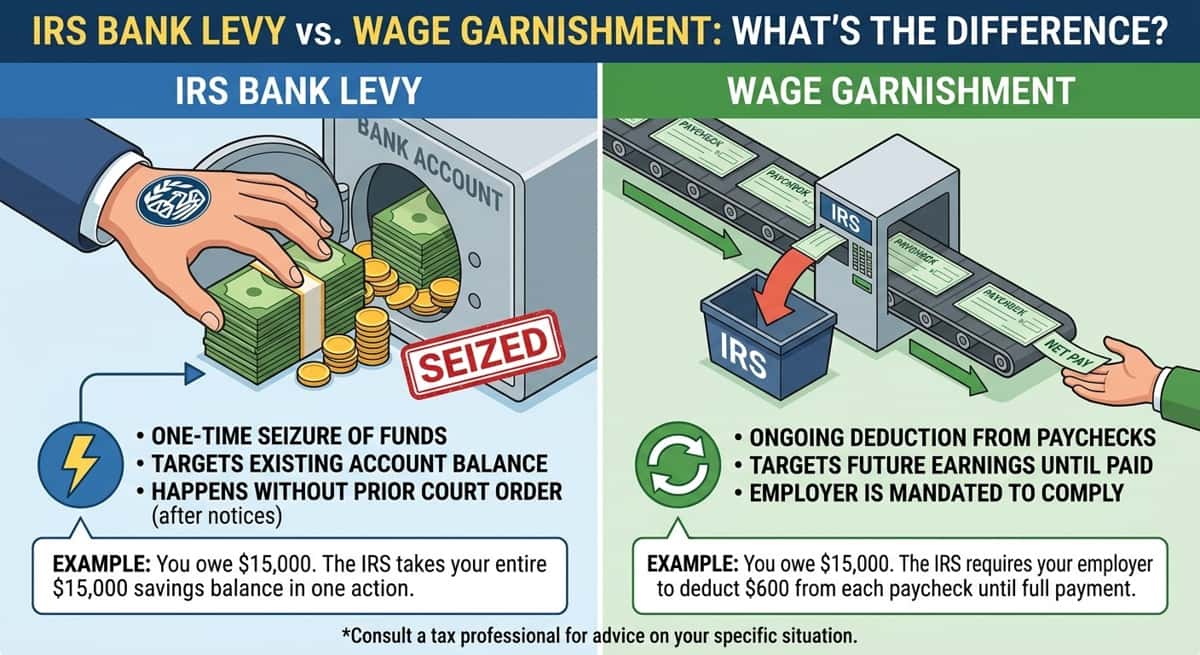
IRS Bank Levy vs. Wage Garnishment: What's the Difference?
An IRS bank levy takes existing funds directly from your account in a single action, following a 21-day holding period. In contrast, wage garnishment continuously deducts a percentage of every paycheck. Both actions stem from unaddressed tax notices but can be stopped through payment plans or hardship releases.
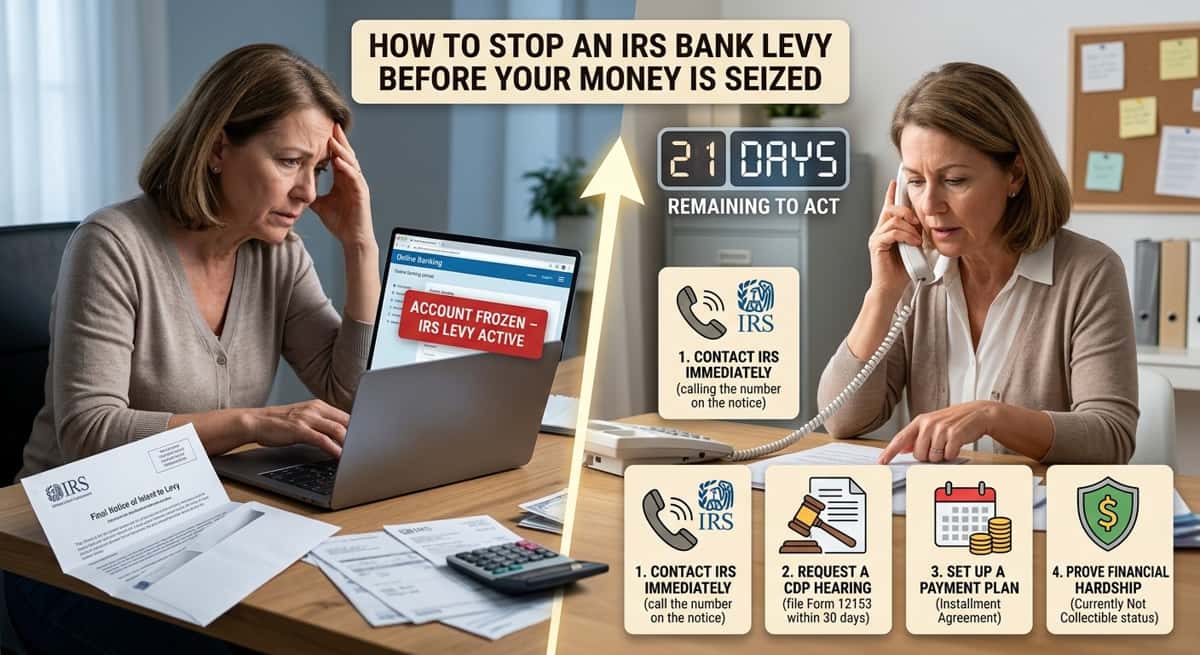
How to Stop an IRS Bank Levy Before Your Money Is Seize
An IRS bank levy legally freezes your funds to settle unpaid taxes. Once notified, you have a 21-day window before your bank transfers the money. You can stop the levy by requesting a formal hearing, setting up an installment agreement, proving financial hardship, or negotiating a settlement through an Offer in Compromise.
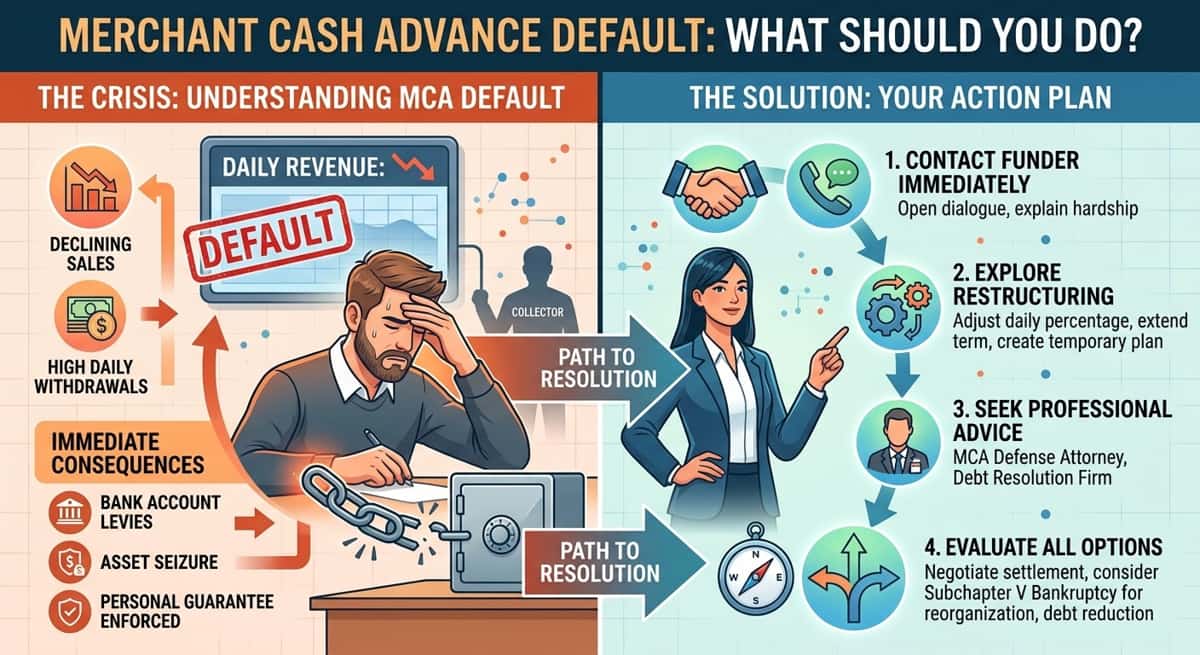
Merchant Cash Advance Default: What Should You Do?
Defaulting on a Merchant Cash Advance (MCA) leads to aggressive collections, bank account freezes, and personal liability under guarantees. To navigate a default, avoid taking new advances to cover existing debt. Instead, gather contracts, maintain lender communication, and consult a debt attorney to explore settlement, restructuring, or bankruptcy options.
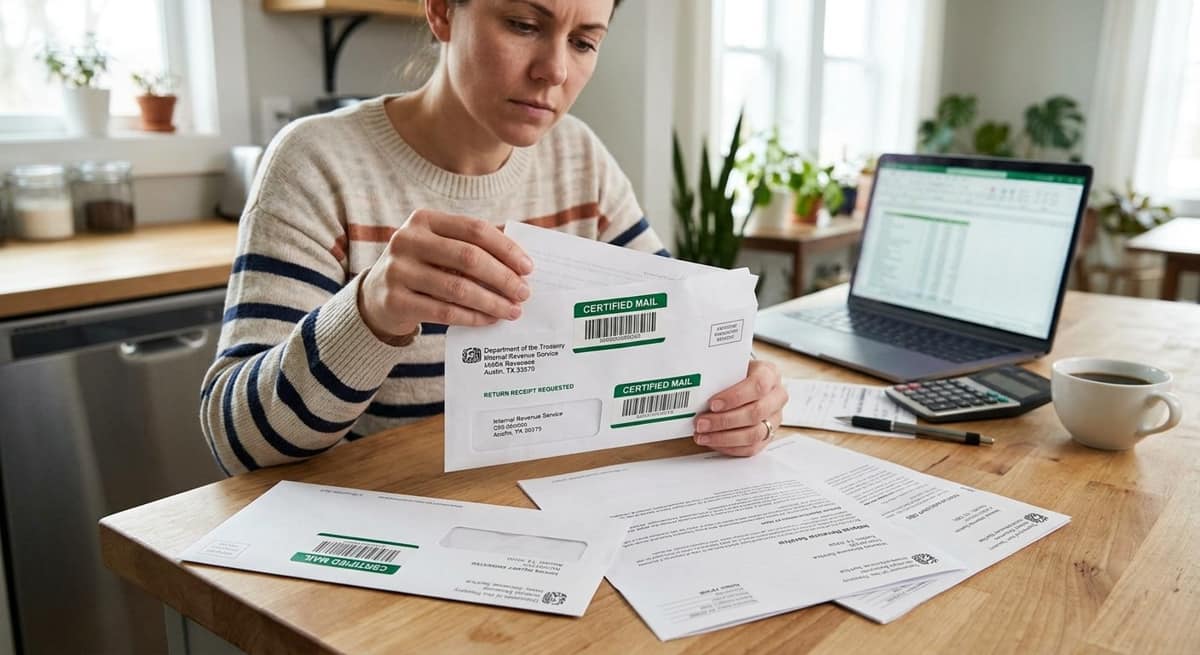
IRS Certified Mail Audit Letters: The Different Types And What You Should Do
IRS certified mail provides official, time-sensitive notice, not proof of illegal activity or immigration trouble. Verify notice numbers on IRS.gov to avoid scams, carefully note response deadlines, and reply calmly in writing with supporting records. For complex business audits or back taxes, consult a CPA, EA, or tax attorney.
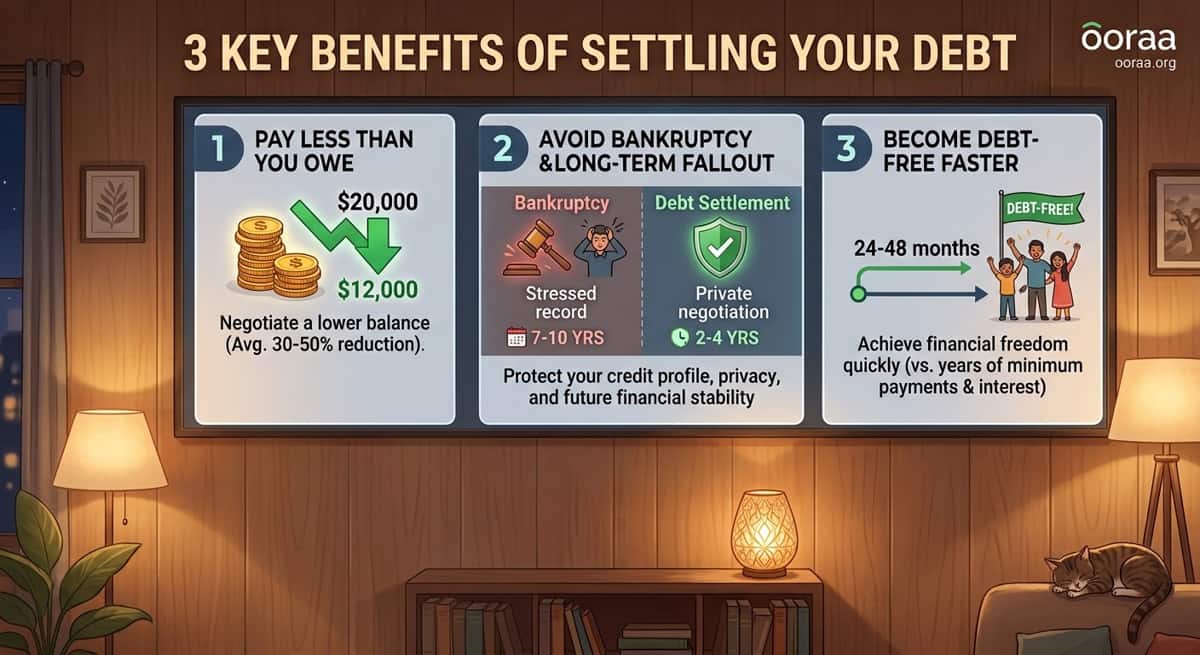
3 Key Benefits of Settling Your Debt
Debt settlement helps families resolve unsecured debts by negotiating a single reduced payment typically 30% to 50% less than owed. It offers a private, faster path to becoming debt-free in 24 to 48 months, allowing you to avoid bankruptcy while balancing personal goals and family financial obligations.
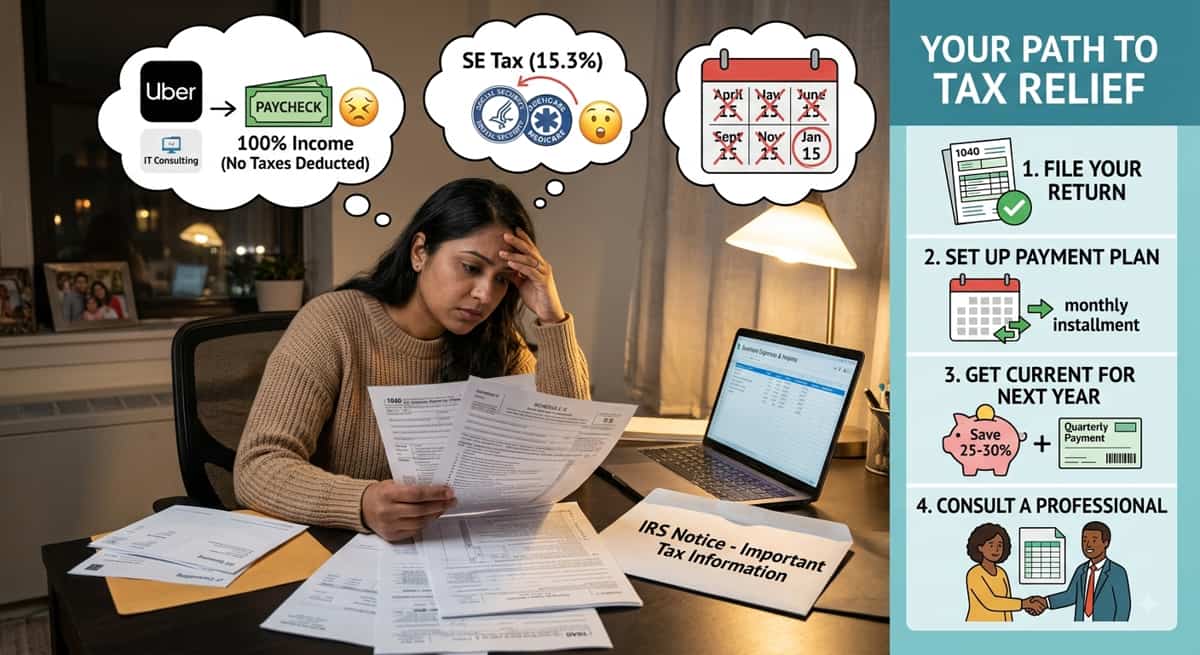
Self-Employed and Owe Taxes? A Guide for 1099 Workers
Self-employed 1099 workers often face unexpected IRS tax bills due to missing withholdings and self-employment taxes. Ignoring tax debt leads to compounding penalties, liens, or levies. Fortunately, manageable solutions exist: always file on time, establish payment plans, request penalty relief, and consult professionals to regain complete financial peace of mind.
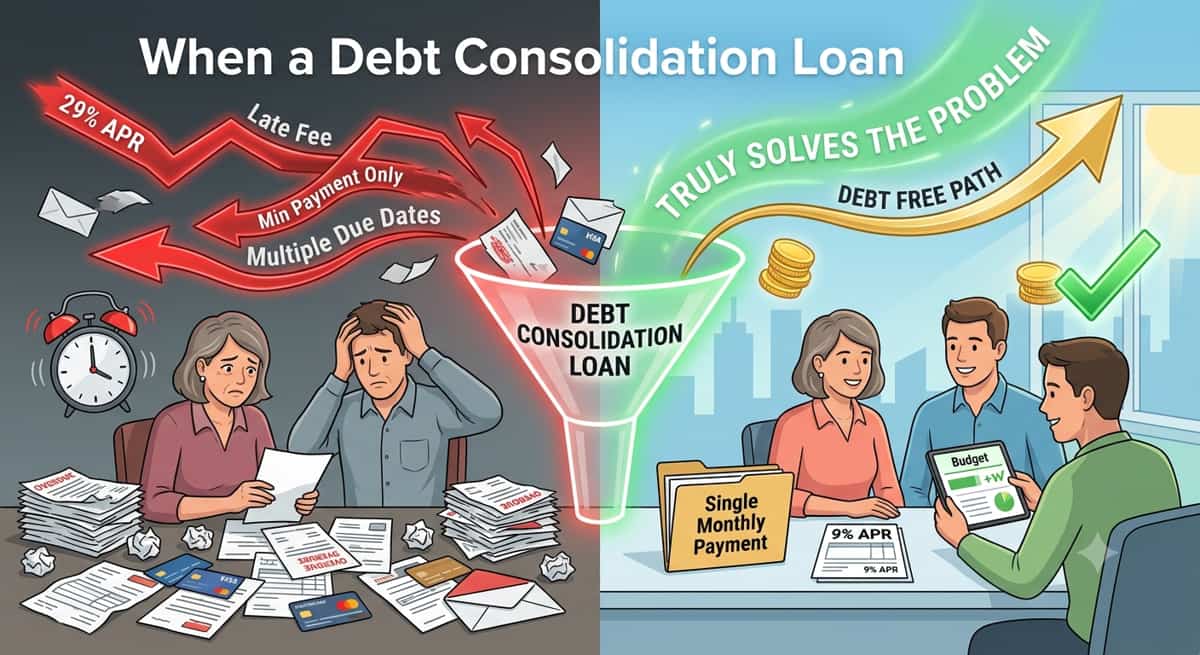
When a Debt Consolidation Loan Truly Solves the Problem
Debt consolidation simplifies multiple high-interest balances into a single monthly payment. It truly works when it reduces your overall interest rate, fits a stable budget, and inspires lasting spending habits. Without addressing root behaviors, consolidation merely delays financial trouble, making alternative debt relief strategies a smarter path.