5 Reasons Your Debt Consolidation Loan Was Denied
Getting turned down for a debt consolidation loan can be frustrating, especially when you're trying to manage multiple debts and make your monthly payments more manageable. Maybe you were hoping to combine several credit card balances or other debts into one loan, but the lender said no.
The good news is that a rejection doesn't mean you're out of options. Lenders look at several things before approving a loan, such as your credit score, income, debt-to-income (DTI) ratio, payment history, and existing debts. Even a small problem on your credit report or an inconsistent income can hurt your chances.
So, instead of getting discouraged, take some time to understand why your application was denied. Knowing what went wrong can help you make better financial decisions and improve your chances next time. Let's look at the common reasons debt consolidation loans get denied and what you can do about them.
What a Loan Denial Means, and What to Do First
When a lender turns you down because of information in your credit report, it must send you a written notice called an adverse action notice. Look for three things. First, the credit score the lender used. Second, the main factors that pulled that score down. Third, the name, address and phone number of the credit reporting company that supplied your report. If the notice doesn't list the specific reasons for the denial, it should say you can ask for them within 60 days. Keep this letter. It's your best clue.
Pull your free credit report within 60 days
After a denial, you can ask the credit reporting company named in the notice for a free copy of your report within 60 days. Read it line by line. If you find a mistake, dispute it with both the credit reporting company and the business that reported it. The credit reporting company must investigate and correct real errors. If you still disagree afterward, you can usually add a short statement to your report.
Pause before reapplying
It's tempting to apply somewhere else right away. Try to wait. Each application can leave a mark on your report, and if the underlying problem is still there, you'll likely get the same answer. Find the reason first, fix it, and then apply again.
Reason 1: Your Credit Score or Credit History Is Below the Lender's Minimum
Every lender sets a minimum credit score, and many also want to see a track record of managing credit in the US. If your score falls below that line, or your file is too new or too small to score well, a lender may say no even when your income is steady.
How lenders read your score and history
Your credit score is a number that summarizes how you've handled borrowed money. Lenders look at whether you pay on time, how much of your card limits you use, how long your accounts have been open, and how often you apply for new credit. A short history, often called a thin file, gives lenders less to go on, so they treat it as higher risk. Each lender sets its own cutoff, so a score that works at one lender may fail at another.
Why this hits newcomers harder
If you built a strong financial record in India, Pakistan, Bangladesh, Sri Lanka, Nepal or another country, it usually doesn't follow you to the US. Foreign credit history typically doesn't count toward a US credit score. Many lenders also like to see two to three years of US credit history. So you can be an excellent borrower back home and still look brand new here. This is one of the most common reasons newcomers are turned down, and it says nothing about your character.
How to check and fix it
Start with the score and factors listed in your denial letter, then review your free report. Pay every bill on time, keep credit card balances low compared with your limits, and avoid opening several accounts at once. If your file is thin, a secured credit card or a credit-builder loan can help you build your US credit history. . Progress takes months, not days, so plan for that.
Reason 2: Your Debt-to-Income Ratio Is Too High
Debt-to-income ratio, or DTI, compares what you owe each month with what you earn each month. If too much of your income already goes to debt payments, lenders worry you can't handle another loan, even one meant to simplify your payments.
What DTI is, with an example
To find your DTI, add up your monthly debt payments, such as credit cards, car loans, student loans and personal loans. Then divide that total by your gross monthly income, which is your income before taxes. Here's a made-up example. Say you earn $6,000 a month before taxes and pay $2,400 a month toward debts. Divide $2,400 by $6,000 and you get 0.40, or 40%. Lenders set their own limits, and those limits vary, but a lower ratio generally improves your chances. The lender can tell you which limit applied to you.
Household and family obligations
Many South Asian families share expenses, support parents or relatives, or live in multigenerational homes. That can be a real strength, but lenders mostly see what's on paper: your own income and your own debts. A spouse's or relative's income may not count unless that person applies with you. If someone joins as a co-borrower, their debts and credit history will be reviewed too.
How to lower it
You can improve your DTI by lowering your monthly debt payments or raising your documented income.Paying off the smallest balances, avoiding new debt, and adding income that can be proven, such as a second job or a spouse's income through a joint application, can all help. You can also ask lenders whether a smaller loan or a longer term would bring the monthly payment down. Run the numbers again before you apply.
Reason 3: The Lender Couldn't Verify Your Income or Job Stability
A lender has to feel confident you'll keep earning enough to repay the loan. If it can't confirm your income, or your work history looks short or uneven, it may deny the application even when your credit score is good.
Self-employed, cash-heavy or newly employed applicants
This is common for people who run a family business, work for themselves, drive for a rideshare or delivery app, or receive part of their pay in cash. Lenders commonly ask for recent pay stubs, tax returns, bank statements or 1099 forms. Cash that never reaches a bank account or a tax return is very hard for a lender to count. A new job can also raise questions, especially if you changed fields or moved recently.
Gig income and tax returns
If your income comes from several sources, a lender may want to see the full picture on your tax returns. Income you earned but didn't report is often hard to use for a loan. Filing accurately each year keeps you on the right side of the law, and it also builds the paper trail lenders rely on.
How to strengthen your application
Gather your recent tax returns, bank statements and any contracts or pay records before you apply. Deposit your income into one account so it's easy to trace. If you changed jobs recently, a letter from your employer confirming your role and pay can help. Some people choose to wait until they have a longer work history.
Reason 4: Your Identity, Residency or Immigration Status Didn't Meet the Lender's Rules
Lenders need to be sure who you are, where you live and that you'll be in the country long enough to repay. If your ID, address or immigration status doesn't match their rules, the application can be denied even with strong credit and income.
SSN vs. ITIN, and visa length
Most lenders ask for a Social Security number. Some accept an Individual Taxpayer Identification Number (ITIN), but fewer do. Green card holders usually have the easiest time. Some lenders also work with certain visa holders, especially when the visa lasts through the end of the loan term. Because loans often run several years, a visa that expires sooner can be a problem. Rules differ a lot from lender to lender, so check eligibility before you apply.
Name and address mismatches
Small differences can cause big headaches. A name spelled one way on your passport and another way on your driver's license, a first and last name swapped, a middle name used in some places and not others, or an old address on your credit file can keep a lender's system from matching you. Make sure your name and address are written the same way on your ID, your bank accounts and your credit report.
How to fix it or find a lender that fits
If your status was the issue, ask the lender what it accepts. Credit unions and lenders that serve immigrants may have different rules. Under the Equal Credit Opportunity Act, lenders can look at your immigration status, but they shouldn't base a decision on it alone. If you think you were treated unfairly, you can file a complaint with the Consumer Financial Protection Bureau (CFPB). A co-signer with strong credit, or a secured loan backed by savings or a vehicle, may also improve your chances.
Reason 5: Your Report Has Errors, Recent Late Payments or Too Many Recent Applications
Sometimes the problem is simply on your credit report: a mistake, a recent late payment, or several credit applications in a short time. Any of these can lower your score or make a lender nervous right when you apply.
Errors and late payments
Credit reports can contain mistakes. Look for accounts that aren't yours, balances that are wrong, payments marked late when you paid on time, and old accounts that should have been closed. Recent late payments can weigh heavily because lenders care a lot about recent behavior. An accurate late payment generally stays on your report for years, so the best move is to make every payment on time from here on.
Multiple applications and high card balances
Applying with several lenders in a short time can create several inquiries on your report, which may look like you're under financial stress. Carrying card balances close to your limits can also hurt your score. Paying those balances down before you apply often helps.
How to dispute and rebuild
To dispute an error, contact both the credit reporting company and the business that reported it, explain what's wrong, and include proof such as statements or receipts. The credit reporting company must investigate. Once your report is accurate, give your score time to recover by paying on time and keeping balances low before you apply again.
Your Options After a Denial
A denial closes one door, not all of them. Here are common debt relief options, with what each can and can't do.
Option | How it helps | Trade-offs | Often suits |
Co-signer or co-borrower | Adds a second person's credit and income | They're responsible if you stop paying, which can strain relationships | People with a trusted, credit-strong relative or friend |
Secured loan | Backed by savings or a vehicle, so the lender takes less risk | You can lose the collateral if you miss payments | People with savings or a car they own |
Credit union loan | May have more flexible rules | Often requires membership | Steady earners with a short credit history |
Nonprofit credit counseling or debt management plan | A counselor reviews your budget and may arrange a plan with your creditors | May involve a monthly fee and limits on new credit | People juggling several card payments |
Debt settlement or bankruptcy | Can reduce or end some debts | Can seriously hurt your credit for years; forgiven debt may be taxable | A last resort, after talking with a licensed professional |
How to choose
Start with the reason you were denied. If it was your credit history, building credit or adding a co-signer may fit.If your debt is too high compared with your income, a counseling agency can help you build a customized debt management plan before you borrow more. If paperwork was the issue, fix it and try a lender that accepts your documents. Whatever you choose, compare costs, read every term, and take your time. No legitimate option promises instant results. A free session with a nonprofit credit counselor can help you decide.
Debt Relief Scams After a Denial
When you're stressed about debt, scammers know it. After a denial you may get calls, texts or ads promising instant relief. Be careful. The FTC says only scammers ask you to pay before they've settled any of your debts or enrolled you in a debt management plan. Walk away from anyone who guarantees to settle all your debts, promises fast forgiveness, or contacts you out of the blue asking for personal or financial details. Reputable credit counselors usually send free information first and review your whole situation before charging for help. Settlement also has costs: it can hurt your credit, and forgiven debt may count as taxable income. If you spot a scam, report it at ReportFraud.ftc.gov.
Next Steps
A denial is frustrating, but it also gives you information. Now you know what to look at, and you can start today. Begin with your denial letter and your free credit report. If you'd like a second set of eyes, schedule a free consultation with an Ooraa credit counselor who can review your full financial picture. Small steps, taken in order, add up.
FAQs
Does a denial hurt my credit?
A denial on its own doesn't lower your score. But applying usually creates a hard inquiry, which can lower your score slightly for a while. Several applications close together can add up, so avoid applying everywhere at once.
How long should I wait to reapply?
There's no single waiting time that fits everyone. What matters more is fixing the reason you were denied. Review your notice, check your report, and apply again once the problem has improved. Applying too soon often brings the same answer.
Can I get a debt consolidation loan with an ITIN?
Some lenders accept an ITIN, but many require a Social Security number, so your options are narrower. Credit unions and lenders that serve immigrants are good places to start. Ask about requirements first so you don't add an unnecessary inquiry.
Can a co-signer help?
It can. A co-signer with strong credit and income may help you qualify or get better terms. But they become legally responsible if you stop paying, so choose someone you trust and talk openly about the risks first.
Will a debt management plan hurt my credit?
It can affect your credit in different ways. Accounts included in the plan may be closed, which can lower your score at first. Over time, steady on-time payments can help. Ask any counselor how a plan would affect you before you enroll.
Ready to Get Started?
Get a free consultation with a certified debt consultant to see if debt settlement is right for you.
Get Free ConsultationAbout the Author
Bhupinder Bajwa
.
Related Articles
How to Get a Debt Consolidation Loan With Bad Credit
11 min read
What Are Debt Relief Loans?
10 min read
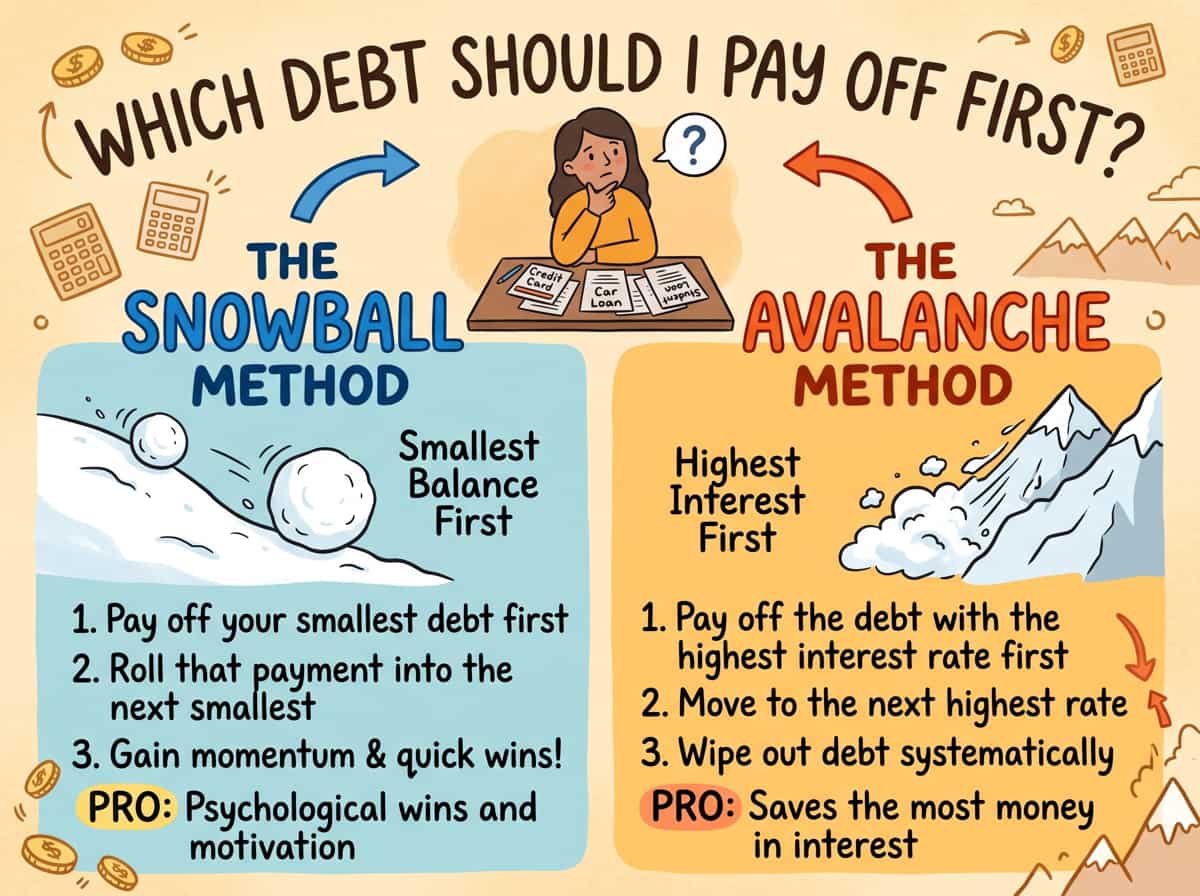
Which Debt Should I Pay Off First?
10 min read
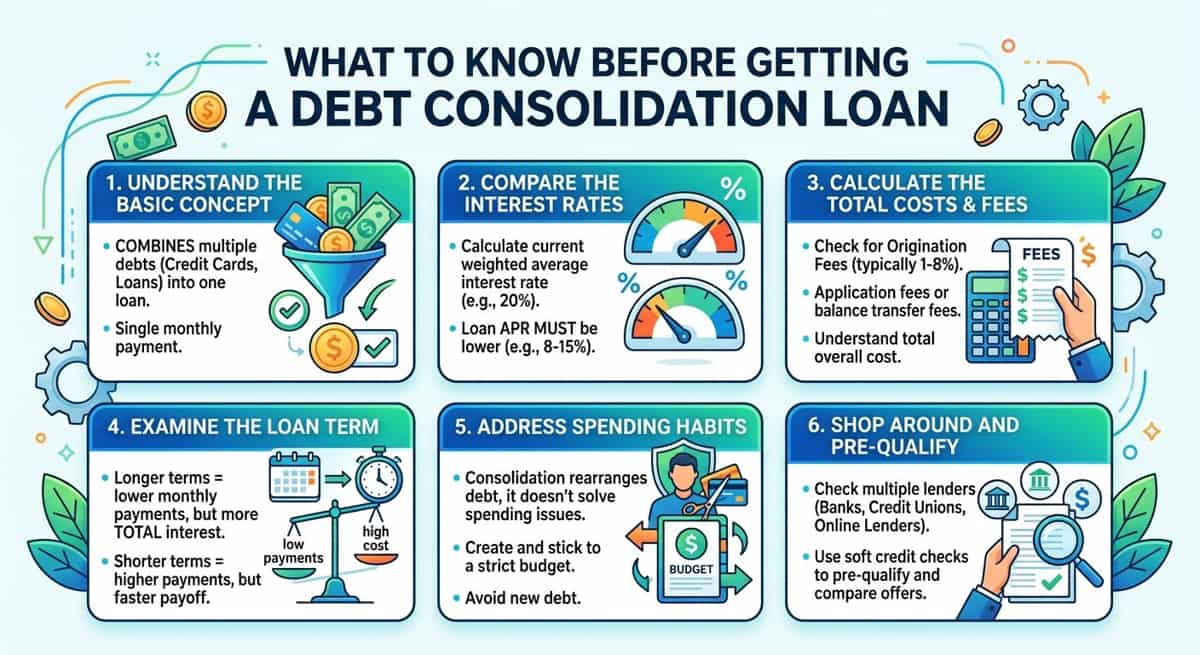
What to Know Before Getting a Debt Consolidation Loan
10 min read
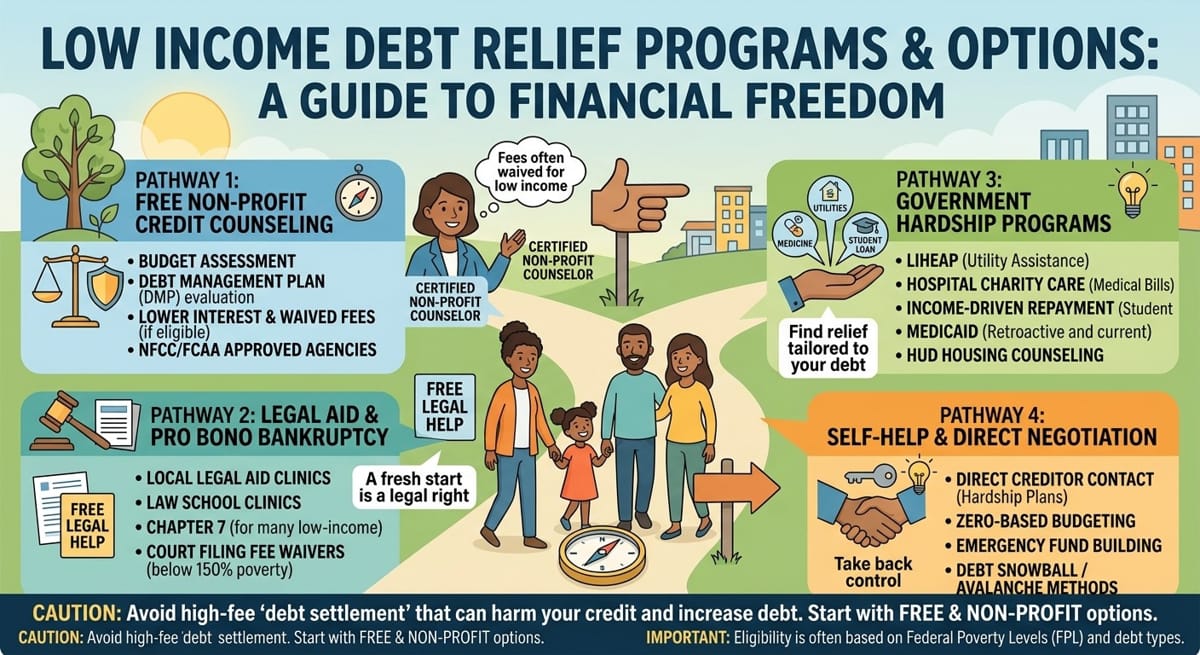
Low Income Debt Relief Programs And Options
14 min read
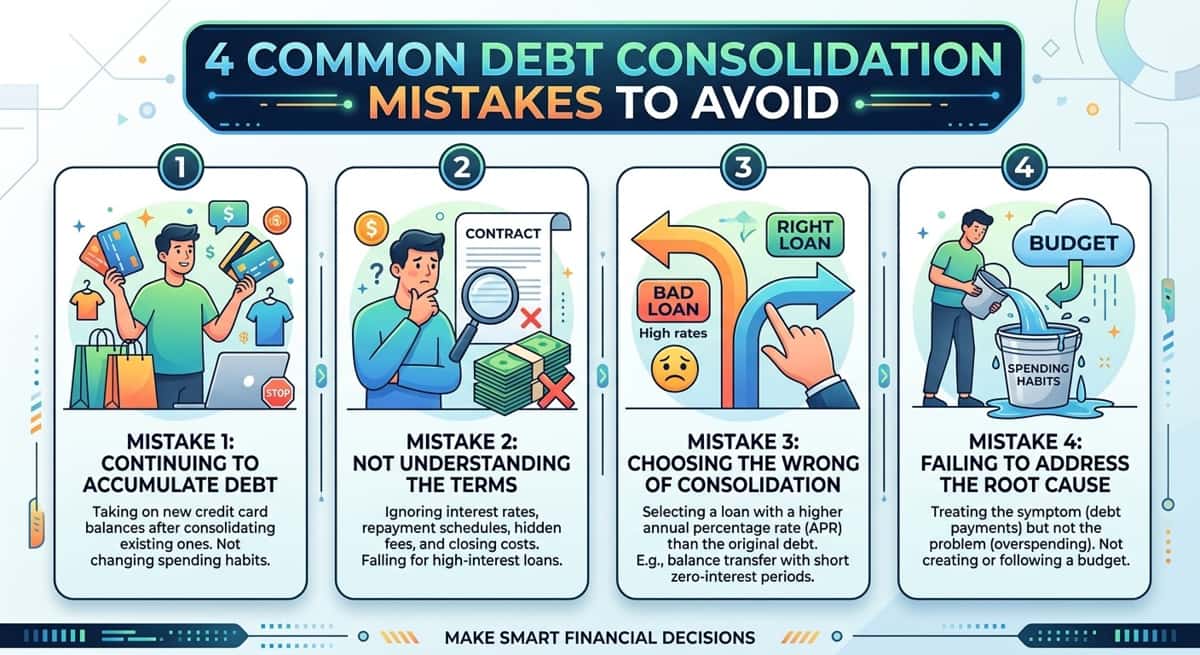
4 Common Debt Consolidation Mistakes to Avoid
10 min read
Get Your Free Consultation
Speak with a certified debt consultant to explore your options.
Start NowNo obligation • Free consultation
Related Posts
- How to Get a Debt Consolidation Loan With Bad Credit
11 min read
- What Are Debt Relief Loans?
10 min read
- Which Debt Should I Pay Off First?
10 min read
- What to Know Before Getting a Debt Consolidation Loan
10 min read