5 Debt Relief Myths and Realities
If you’re struggling with debt in the U.S., it can feel like you’re the only one. You’re not.
Many South Asian families are juggling more than a credit card bill. You might be building credit from zero after moving here. You might be sending money home to parents every month. You might be on a work visa, where a layoff or a missed payment feels like a bigger risk. Or you might be paying for a medical emergency, a wedding, or a child’s education.
When money gets tight, the instinct is often to handle it quietly. That’s where myths creep in. Some people avoid getting help because they fear what it will do to their credit, their visa, or their family’s name. Others trust the first company that promises a quick fix.
Myth 1: “Debt Relief Will Wipe Out What I Owe”
The myth: Many people believe that joining a debt relief program will shrink their balance to almost nothing, or make it disappear completely.
Why it sounds true: Ads are full of bold promises like “erase your debt” or “settle for pennies on the dollar.” When you’re stressed and the bills keep arriving, a message like that is hard to ignore. A friend or cousin telling you about a success story makes it feel even more believable.
The reality: Most debt relief programs reduce what you owe, lower your interest, or turn many payments into one. None can promise your debt will vanish. What you actually get depends on your creditors, your income, and the type of debt you have.
Here are the main debt relief options in plain terms:
Option | What it is | Main trade-off |
Debt management plan | A nonprofit counselor works with your creditors to lower interest. You make one monthly payment. | You repay what you owe, usually over several years. |
Debt settlement | You try to pay creditors less than the full balance. | Takes time, creditors can say no, and your credit usually drops. |
Debt consolidation | You combine balances into one loan with one payment. | Works best if you qualify for a lower rate. |
Bankruptcy | A legal process that can discharge or restructure debt. | Serious long-term credit impact. Talk to an attorney first. |
A simple example. Say Priya, a software engineer on a work visa, has about $15,000 across three credit cards. Most of her payment each month goes to interest.
With a debt management plan, her counselor asks the card companies to lower the interest. She pays one amount each month and repays the full balance over a few years. It isn’t fast, but it’s predictable.
With a debt resolution and settlement program, she may stop paying her creditors while she saves money for settlements. Collection calls can continue, her credit will likely drop, and a creditor could sue her. If a creditor forgives part of the debt, that amount may count as taxable income.
This is a made-up example to show how the choices differ. It’s not a promise of any result.
What to watch for: Be careful with any company that says “guaranteed,” “pennies on the dollar,” or “we’ll stop all your collection calls.” Honest providers talk about the downsides first.
Myth 2: “Debt Relief Will Ruin My Credit Forever”
The myth: Many people believe that once you use debt relief, your credit is destroyed for good, and you’ll never get a loan, a car or an apartment again.
Why it sounds true: In the U.S., a credit score affects almost everything: renting, car loans, even some jobs. Some debt relief options really do cause a big drop. If you’ve worked hard to build a score from nothing, losing it feels like losing years of effort.
The reality: Some options lower your credit score, but the effect isn’t permanent, and you can rebuild. A debt management plan may have a smaller effect, while debt settlement affects your credit score and bankruptcy usually have larger impacts. Negative items typically stay on your credit report for several years and then fall off. Ask any provider for the exact timelines.
If you’re new to the U.S., timing matters. A thin credit file means a few late payments or one collection account can pull your score down faster than it would for someone with a long history. That’s one more reason to get help early, before accounts go to collections.
You can rebuild. Here are common steps:
Pay every bill on time. Payment history matters a great deal.
Use a secured credit card and keep the balance low.
Try a credit-builder loan, which some credit unions offer.
Check your credit reports for free and dispute any mistakes.
Compare it with doing nothing. Missed payments, collections and lawsuits hurt your credit too, and they come with growing interest and fees. For many people, the real choice isn’t “relief or perfect credit.” It’s “a plan now, or a bigger problem later.”
Myth 3: “If I Ignore the Debt, It Will Go Away”
The myth: Many people believe that if they stop answering calls and opening letters for long enough, the debt will eventually disappear.
Why it sounds true: Some old debts do become too old for a creditor to sue over, so people hear “it expires” and assume the problem solves itself. Avoiding the stress also feels better today, even if it costs more tomorrow.
The reality: Debt rarely disappears on its own. Ignoring it can lead to collection calls, lawsuits and, in some cases, wage garnishment. In the meantime, interest and fees keep adding to the balance.
Here’s what can happen if you don’t pay:
Collection calls and letters.
A lawsuit from the creditor or a debt buyer.
A court judgment against you.
Wage garnishment after a judgment, in many cases.
What about the time limit? Every state has a statute of limitations, which limits how long a creditor can sue you over an old debt. The time period varies by state and by type of debt. In some states, even a small payment can restart the clock, so check your state’s rules before you pay anything on a very old debt.
Know your rights. Under the Fair Debt Collection Practices Act, you can ask a debt collector to prove that the debt is yours. You generally have a limited window after their first notice to ask in writing, so read that first letter carefully. The Consumer Financial Protection Bureau (CFPB) offers sample letters and plain-language guides on its website.
One rule above all: never ignore a court summons. If you don’t respond, the court may rule against you automatically. Contact a nonprofit credit counselor or a legal aid office right away.
Myth 4: “Asking for Help Will Hurt My Immigration Status or My Family’s Reputation”
The myth: Many people believe that talking to a debt counselor could put a visa or green card at risk, or that the community will find out and judge the family.
Why it sounds true: Immigration rules are complicated, and stories travel fast through WhatsApp groups and community circles. When your status depends on a job or a sponsor, taking any risk feels impossible.
The reality: Getting ordinary debt counseling is generally private and isn’t an immigration issue by itself. A few situations are worth checking with an immigration attorney.
On immigration: Talking to a credit counselor or setting up a repayment plan isn’t breaking any rule. Things can get more serious with:
Bankruptcy filings.
Unpaid taxes.
Giving false or incomplete information on any form or application.
If you’re on a work visa or have a green card application in progress and you’re considering bankruptcy or settlement, speak with an immigration attorney first. A short consultation now can save you a lot of stress later.
On family and community: Reputable credit counseling is confidential. While deciding to talk to your partner about debt is a personal choice, you don’t have to tell your Debt is common, and it’s often caused by things outside your control: a layoff, a medical bill, helping relatives overseas. Getting help early shows responsibility, not failure.
Two quieter risks to watch. Informal arrangements like community lending circles or loans from relatives can work well. But without clear terms, they can strain relationships when payments are missed. Also, putting money you send abroad on a credit card can add up quickly in interest. If you do either, write down the terms and make a plan you can actually keep.
Myth 5: “All Debt Relief Companies Are the Same, and Good Help Costs a Fortune”
The myth: Many people believe every company offers the same service, and that anyone willing to help will charge high fees.
Why it sounds true: The ads look alike and the promises sound alike. The first company that calls or messages you can seem like your only choice. If you’ve been burned by a bad deal before, it’s easy to assume everyone is after your money.
The reality: Providers differ a lot in how they work, what they charge and how honest they are. Low-cost and nonprofit options exist.
Credit counseling agencies. Many nonprofits are members of the National Foundation for Credit Counseling (NFCC). They offer budgeting help and debt management plans, often at low cost.
For-profit debt settlement companies. They negotiate with creditors in exchange for a fee. Costs and results vary widely.
Attorneys. A bankruptcy or debt attorney can advise you on legal options, including lawsuits and bankruptcy.
When you compare providers, look at the fees, when you have to pay them, what services you actually get, and whether the company is licensed in your state.
A rule worth knowing. The Federal Trade Commission’s Telemarketing Sales Rule generally bars companies that sell debt relief by phone from charging fees before they’ve actually settled a debt. If a company asks for a big payment upfront, treat that as a warning sign.
How to Spot a Legitimate Provider: A 6-Point Checklist
Before you share personal information or sign anything, run through these:
No upfront fees. You shouldn’t pay before they’ve delivered results.
No guaranteed results. Honest providers can’t promise outcomes.
Fees in writing. You should see exactly what you’ll pay, and when.
Licensed in your state. Look up your state’s rules for debt relief providers.
A clean record. Search the company in the CFPB complaint database and on the Better Business Bureau.
Honest about the downsides. Good counselors explain the risks to your credit, your taxes and possible lawsuits, not just the benefits.
Language help. Some providers offer counseling in South Asian languages such as Hindi, Bengali, Urdu, Punjabi, Tamil and Gujarati. Ask directly, since it varies by provider.
Be careful on social media. Scammers often target immigrant communities through WhatsApp, Facebook groups and direct messages, with “debt elimination” offers. Never send money or share account details with someone who contacts you first and pressures you to act fast.
Your Next Step
Here’s what to take away:
No honest provider can promise to erase your debt.
Your credit can recover, and doing nothing often costs more.
Asking for help is private, and it’s a smart, responsible move.
If you’d like to talk through your options, contact us for a free, no-obligation consultation. There’s no pressure, and you decide what happens next.
Frequently Asked Questions
Does debt relief affect my green card or visa?
Ordinary credit counseling and repayment plans generally aren’t an immigration issue. Bankruptcy, unpaid taxes or inaccurate information on an application can be. If any of those apply to you, talk to an immigration attorney before you decide.
How long does debt relief take?
It depends on the option. A debt management plan often runs several years. Settlement can take a long time too, and there’s no guarantee your creditors will agree. Ask any provider for an honest estimate in writing.
Is debt settlement taxable?
Often, yes. If a creditor forgives part of your debt, the forgiven amount may count as taxable income, and you may get a tax form (Form 1099-C). Some exceptions exist, so ask a tax professional about your situation.
Can I get help if I have no credit history?
Yes. Nonprofit credit counselors can help with budgeting and repayment plans even if your credit file is thin. They can also guide you on building credit once your debts are under control
Ready to Get Started?
Get a free consultation with a certified debt consultant to see if debt settlement is right for you.
Get Free ConsultationAbout the Author
Bhupinder Bajwa
.
Related Articles
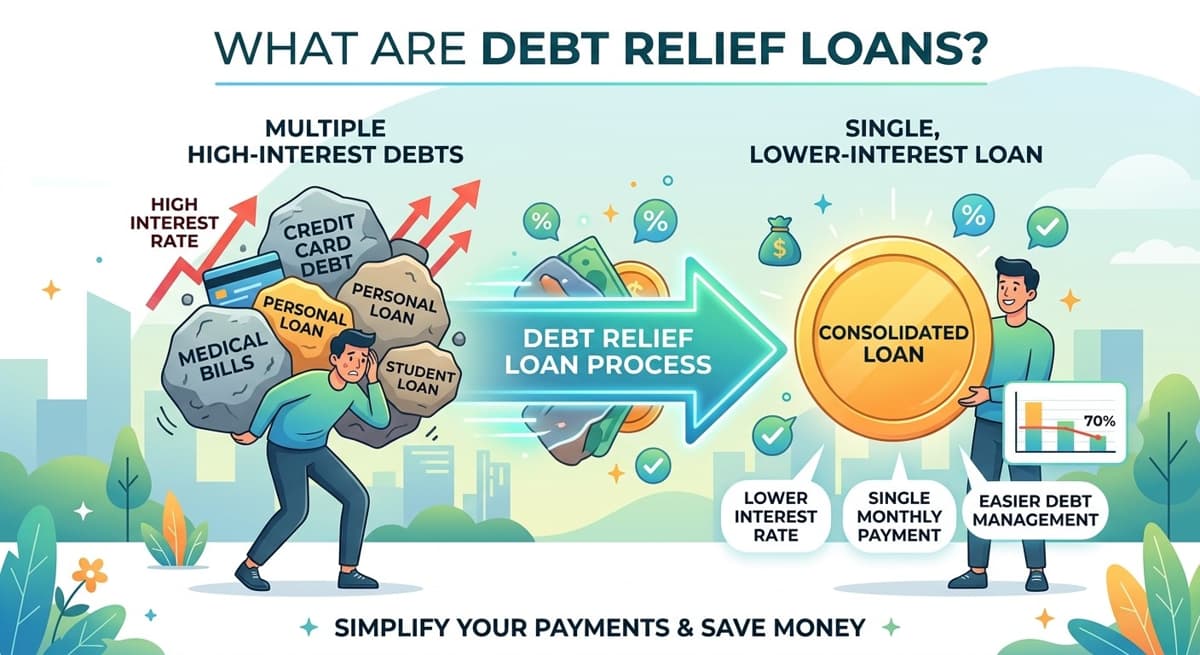
What Are Debt Relief Loans?
10 min read
What’s It Like to Go Through Debt Relief
10 min read
Which Debt Should I Pay Off First?
10 min read
Low Income Debt Relief Programs And Options
14 min read
What Debts Can Be Included in Debt Relief?
13 min read
Debt Consolidation vs. Debt Relief: Which Option Fits Your Situation?
10 min read
Get Your Free Consultation
Speak with a certified debt consultant to explore your options.
Start NowNo obligation • Free consultation
Related Posts
- What Are Debt Relief Loans?
10 min read
- What’s It Like to Go Through Debt Relief
10 min read
- Which Debt Should I Pay Off First?
10 min read
- Low Income Debt Relief Programs And Options
14 min read