Understanding the Basics: What is Chapter 13 Bankruptcy?
Chapter 13 bankruptcy is a legal process known as a reorganization bankruptcy. It's designed specifically for individuals with a steady, reliable income who need help managing their debt but want to avoid selling off their property. Think of it not as a way to wipe out your debts completely, but as a structured plan to pay back a portion of what you owe over a set period. This is the core difference between Chapter 13 and Chapter 7 bankruptcy. In a Chapter 7 bankruptcy, a trustee liquidates (sells) a debtor's non-exempt assets to pay off creditors. The remaining eligible debts are then discharged. With Chapter 13, you keep your assets. Instead, you enter into a repayment plan that typically lasts three to five years. During this time, you make regular, court-ordered payments to a trustee who then distributes the money to your creditors. One of the most significant features of Chapter 13 is the automatic stay, which takes effect the moment you file. This legal protection immediately stops most collection activities, including harassing phone calls, foreclosure proceedings, repossessions, and lawsuits. This provides a crucial window of relief. The repayment plan also allows you to catch up on missed mortgage or car payments and restructure your debts, so you can keep your home, car, and other valuable assets. In a Chapter 13 filing, you can generally keep all of your assets, as long as you can afford to pay for them under the court-approved plan.Is Chapter 13 the Right Fit? A Closer Look at Your Situation
When Chapter 13 Makes Sense
Consider these scenarios, which may feel familiar:- The Homeowner: A young professional who recently took a pay cut or lost a second job, now struggling to keep up with their mortgage. Filing Chapter 13 can help you catch up on missed mortgage payments and keep your home.
- The High-Earner: A physician or engineer with a high income who doesn't qualify for Chapter 7 bankruptcy, but is overwhelmed by student loans and credit card debt. Chapter 13 provides a way to restructure these debts without the stress of asset liquidation.
- The Business Owner: An individual with a family business (a sole proprietorship) who has personally guaranteed business debts. Chapter 13 can consolidate both personal and business debts, giving them a fresh start.
The Chapter 13 Process: What to Expect on Your Journey
Step 1: Credit Counseling & Paperwork Preparation
Before you can file, you must complete a credit counseling course from an approved agency. This is a mandatory step that helps you explore all your financial options. Following the counseling, you will work with your attorney to gather extensive documentation, including pay stubs, tax returns from the past four years, bank statements, and a detailed list of all your debts and assets.Step 2: Filing and the Automatic Stay
Once all the paperwork is meticulously prepared, your attorney will file the petition with the bankruptcy court. The moment this is done, the automatic stay goes into effect. This powerful injunction immediately stops most creditors from taking collection actions against you, offering you much-needed relief from calls, foreclosures, and lawsuits.Step 3: The Payment Plan and Creditors' Meeting
Within a few weeks of filing, you will propose a repayment plan. The amount you pay is based on your "disposable income"—what is left over after you've paid for necessary living expenses. The plan must ensure that secured creditors (like your mortgage and car loan lenders) and priority creditors (such as for child support or recent tax debts) are paid in full. Payments to unsecured creditors (like credit card companies) can be as low as what they would have received in a Chapter 7 liquidation. Within about 30 to 45 days, you will attend a "meeting of creditors" with your attorney and the court-appointed trustee to review your financial situation and proposed plan.Step 4: The Confirmation Hearing & Plan Completion
The court will then hold a confirmation hearing to approve your plan. Once confirmed, you must diligently make the monthly payments for the duration of the plan, which is typically three to five years. This is a legally binding commitment. Successfully completing the plan leads to the discharge of remaining eligible debts, providing a true fresh start. Note: Navigating this process is complex and the rules are unforgiving. Attempting to file without legal counsel can lead to critical errors, including case dismissal. This information is a general overview and not legal advice. I strongly urge you to consult with a qualified bankruptcy attorney to assess your specific situation and guide you through the process, ensuring all legal requirements are met.Pros and Cons: Weighing Your Options
The Pros: A Path to Stability
The biggest benefit is the automatic stay, which stops most creditor actions the moment you file. This provides immediate relief from relentless phone calls, threatening letters, and pending lawsuits. Chapter 13 also allows you to keep your most valuable assets, like your home and car, which would likely be at risk in a Chapter 7 filing. By including all your debts in a single, court-approved repayment plan, you consolidate what could be dozens of payments into one manageable monthly installment, making it easier to budget and regain control.The Cons: The Cost of a Fresh Start
On the other hand, Chapter 13 requires a significant long-term commitment. You're locked into a rigid 3-to-5-year plan that you must follow diligently. A single missed payment can put your entire case at risk. The process also has a significant negative impact on your credit score, which can make it difficult to secure loans or credit in the near future. Lastly, unlike Chapter 7, Chapter 13 requires you to pay for your attorney’s services, and these legal fees can be a barrier for those already in a precarious financial position.A Glimpse Beyond Bankruptcy: Alternative Debt Relief Solutions
While Chapter 13 is a powerful solution, it's not the only one. For some, it might not be the right fit, especially if you want to avoid a long-term court-mandated plan or if your debt levels fall below the bankruptcy threshold. Before making a final decision, it's wise to consider other proven methods of debt relief. Alternatives such as debt settlement and debt consolidation can provide a viable path to financial freedom without filing for bankruptcy. Debt consolidation involves combining multiple high-interest debts into a single, more manageable loan, often with a lower interest rate, to simplify payments. In contrast, debt settlement involves negotiating with your creditors to pay a portion of the debt you owe, ultimately reducing the total amount you have to pay back. These options may be particularly appealing if you have steady income but are struggling with overwhelming credit card or medical debt.Making an Informed Decision for Your Financial Future
Deciding on Chapter 13 bankruptcy is a complex choice that requires careful consideration of your unique financial situation and long-term goals. It offers a structured way to keep your assets and regain control, but it is a serious legal commitment. The best path forward is not a one-size-fits-all solution. To ensure you make the most informed decision for your family and future, I strongly encourage you to speak with a qualified debt relief professional. We are here to listen with empathy and provide expert guidance on all your options, helping you choose the path that leads to a brighter, more stable financial future.Ready to Get Started?
Get a free consultation with a certified debt consultant to see if debt settlement is right for you.
Get Free ConsultationAbout the Author
Bhupinder Bajwa
Bhupinder Bajwa is a Certified Debt Specialist and Financial Counselor with over 10 years of experience helping families overcome financial challenges. Having worked extensively with the South Asian community in the U.S., he understands the cultural nuances and unique financial hurdles they may face. He is passionate about offering clear, compassionate, and actionable guidance to help individuals and families achieve their goal of becoming debt-free.
Related Articles
Is 639 A Good Credit Score? How It Affects Loans, Credit Cards And Ways To Improve It
12 min read
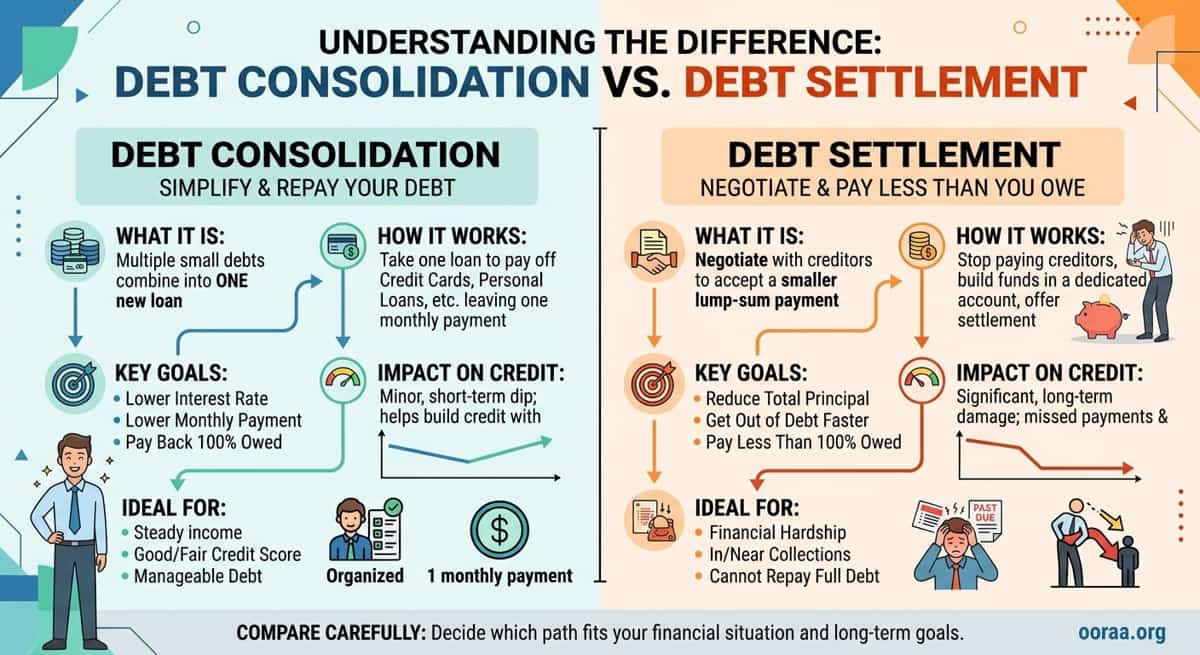
What’s The Difference Between Debt Consolidation And Debt Settlement?
12 min read
Can You Consolidate Debt With a Low Credit Score?
11 min read
Self-Employed and Owe Taxes? A Guide for 1099 Workers
11 min read
How Much Tax You Pay On Lawsuit Settlements
9 min read
Commercial Debt Management: What Business Owners Should Know
11 min read
Get Your Free Consultation
Speak with a certified debt consultant to explore your options.
Start NowNo obligation • Free consultation
Related Posts
- Is 639 A Good Credit Score? How It Affects Loans, Credit Cards And Ways To Improve It
12 min read
- What’s The Difference Between Debt Consolidation And Debt Settlement?
12 min read
- Can You Consolidate Debt With a Low Credit Score?
11 min read
- Self-Employed and Owe Taxes? A Guide for 1099 Workers
11 min read